Will Low Interest Rates Continue?

The Mortgage Corner

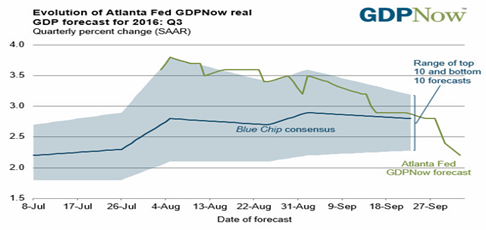
This question is behind much of the stock and bond market gyrations. We are near full employment with a 5.0 percent unemployment rate, some 11 million jobs created since the end of the Great Recession, yet we still have record low interest rates. And inflation has barely budged, with GDP growth still struggling in the 2 percent range, and predicted to continue in that range by the Atlanta Federal Reserve Bank.

But beware of the Federal Reserve’s next FOMC meeting in the first week of November. Several Fed Governors now say that it’s time to begin to raise short term rates to dampen any incipient inflation tendencies.
image

Graph: Marketwatch

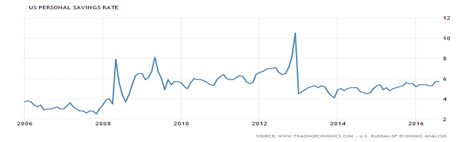
So will such low rates continue? The simplest economic answer is there’s not much demand for money at the moment, in relation to the amount of money either in circulation or being saved by companies and individuals. This is evidenced by the record amount of cash or other readily sellable assets—some $4.5 trillion in such assets are being held by corporations both home and abroad—and the 5.7 percent personal savings rate, which is up from its historical low of 1.9 percent in 2005, per the graph below.
image

Graph: Trading Economics

In other words, even though lots of money is being hoarded in both public and private sectors, many Fed Governors are saying it’s time to raise interest rates. The private sector is investing in new plants and equipment overseas, so it’s not boosting domestic GDP growth, whereas government spending has been shut down by a very conservative Congress.

Austerity policies have ruled, in other words, just as in Europe. The only difference and reason for US growth being faster than Europe’s, is the Fed’s QE purchase of bonds vs. the EU’s almost total refusal to consider it until lately. This has put enough U.S. money into circulation to create 2 percent GDP growth, whereas the EU has suffered 2 recessions since 2008, though EU growth has picked up of late.

It has kept our interest rates at these record lows, and been good for the real estate recovery, of course. But many Fed governors are beginning to make noises that interest rates could rise after their November FOMC meeting, which occurs at the same time as the Presidential election. We can only hope that it will be a onetime rate increase followed by enough time to examine the results.

The reason is housing affordability. First-time homebuyers comprise just 30-32 percent of buyers, down from 40 percent during more normal times. And the NAR’s housing affordability index has dropped 10 percent in just one year, which measures the amount of house someone with a median income can buy. This is mainly due to the fact that the NAR’s median single-family home price has risen 15 percent just this year.

So we need those low interest rates for the housing industry to continue to recover, though we know interest rates will probably rise into next year. But with conforming fixed rates 3.25 percent for a 1 point origination fee, it is still dirt cheap.

Harlan Green © 2016

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen
Posted in Consumers, Economy, Housing, housing market, Politics, Weekly Financial News | Tagged , , , , , | Leave a comment

Jobs Report—Not Yet Full Employment

Popular Economics Weekly

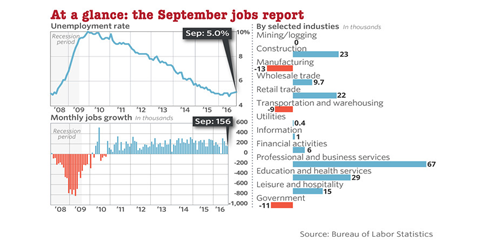
The unemployment rate rose slightly to 5 percent for the first time since April, the government said Friday, though that was mainly because 444,000 people entered the labor force. There are still too many unemployed, in other words. A broader measure of unemployment that includes people who gave up looking for work or can only find part-time jobs was unchanged at 9.7 percent. And it was at 8 percent before the Great Recession.

image

Graph: Marketwatch

Some 3 million people have jointed the labor force in the past year, a clear sign that record job openings and steady hiring are enticing more Americans to seek work. An increasing number of companies even say they have trouble finding enough skilled workers. But there are still more than 7 million that have either stopped looking or can’t find full time jobs.

This is while total employment gains for August and July were 7,000 lower than previously reported in revisions. The government said 167,000 new jobs were created in August instead of 151,000. July’s gain was trimmed to 252,000 from 275,000.

The U.S. has added an average of 178,000 jobs a month this year, down from 228,000 in 2015 and 251,000 in 2014. Hiring was expected to taper off as it usually does when an economic expansion reaches maturity and the pool of jobless workers shrinks.

But the inflation hawks will now cry louder that it’s time to raise the Fed’s short term rates from 0.5 percent—because wages are now rising at 2.6 percent per year, though that isn’t enough to raise the inflation rate. In fact, it hasn’t been enough to raise economic growth, either, which is projected to remain in the 2 percent range this year as it has been for the last 2 years.

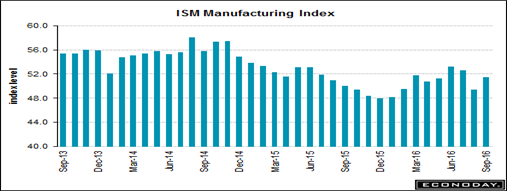
So any boost in the Fed’s interest rates will hurt growth by causing the US dollar’s value to rise against other currencies, which in turn hurts exports and so manufacturing, which barely expanding, according to the latest ISM manufacturing survey.

image

Graph: Econoday

The September ISM Manufacturing Index did bounce more than 2 points higher to a much better-than-expected 51.5, largely because the US Dollar has been weaker of late—due to the fact that the Fed hasn’t raise interest rate. So said higher growth isn’t assured.

New orders are the most important of all readings rose 6 points to a very solid 55.1. Export orders are respectable and steady at 52.0 while the draw in total backlog orders slowed, with this index up 4 points and nearly hitting breakeven 50 at 49.5. Production also improved in the month, up 1.4 points to 52.8, as did employment which, at 49.7, is also nearly at 50. This is a positive report, pointing to rising though no more than moderate strength for the nation’s factory sector.

But alas, beware of those inflation hawks if we want higher growth, and fuller employment for all who want to work. There are two reasons for the Fed to keep interest rates low. Firstly, the energy sector is just beginning to recover from its mini-recession, as crude oil prices inch up to $50 per barrel. And European bond prices are negative with the EU in trouble with Brexit, which means the European Central Bank has to remain in an easing mode. So let’s give this economy a chance to really grow before beginning to raise the all-important Fed funds and overnight rates.

Harlan Green © 2016

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen
Posted in Consumers, Economy, Politics, Uncategorized, Weekly Financial News | Tagged , , , , , , | Leave a comment

Trump the Terrible Demagogue

Popular Economics Weekly

Many Republicans as well as Democrats are horrified at the possibility of a Trump Presidency. It’s not only because of his blatant racism, which he makes no attempt to hide. Or his complete ignorance of foreign policy. He has advocated the arming of Japan and Korea with nuclear weapons—which coupled with his unstable personality that a biographer has labeled psychopathic, makes him a dangerous psychopath.

No, it is because with his slogan Take Back America, he wants to disunite the United States of America. This is when America is already divided—by race and economic opportunity, for starters. Trump seems to want to take America to a time when we were a divided country—to the Civil War.

He is taking advantage of the fact the U.S. Civil War is still being fought in many, particularly southern states, where African-American and other minorities are disproportionally prevented from exercising their voting rights—be it with voter ID requirements, or the even more pernicious felon disenfranchisement laws in many states.

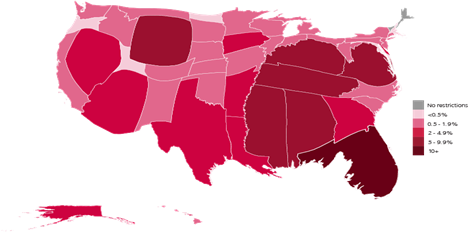
For instance, Iowa, Kentucky, and Florida permanently ban any convicted felon from exercising their right to vote. Only Maine and Vermont give everyone the right to vote, even still imprisoned felons. The rest of the states allow for reinstatement in some form, once their time has been served.

image

Graph: Sentencing Project

The Sentencing Project in a just released study found:

  • As of 2016, an estimated 6.1 million people are disenfranchised due to a felony conviction, a figure that has escalated dramatically in recent decades as the population under criminal justice supervision has increased. There were an estimated 1.17 million people disenfranchised in 1976, 3.34 million in 1996, and 5.85 million in 2010.
  • Approximately 2.5 percent of the total U.S. voting age population – 1 of every 40 adults – is disenfranchised due to a current or previous felony conviction.
  • Individuals who have completed their sentences in the twelve states that disenfranchise people post-sentence make up over 50 percent of the entire disenfranchised population, totaling almost 3.1 million people.
  • Rates of disenfranchisement vary dramatically by state due to broad variations in voting prohibitions. In six states – Alabama, Florida, Kentucky, Mississippi, Tennessee, and Virginia – more than 7 percent of the adult population is disenfranchised.
  • The state of Florida alone accounts for more than a quarter (27 percent) of the disenfranchised population nationally, and its nearly 1.5 million individuals disenfranchised post-sentence account for nearly half (48 percent) of the national total.
  • One in 13 African Americans of voting age is disenfranchised, a rate more than four times greater than that of non-African Americans. Over 7.4 percent of the adult African American population is disenfranchised compared to 1.8 percent of the non-African American population.

It is therefore easy to see why majorities in four states are in the Take Back America column. Florida (21 percent), Kentucky (26 percent), Tennessee (21 percent), and Virginia (22 percent) have the largest percentage of disenfranchised voters—more than one in five African-Americans.

But what if another such demagogue with the thirst for absolute power—both Trump and Veep Mike Pence have said Vladimir Putin and even N. Korea’s Kim Jong Un are stronger leaders than President Obama—is able to disguise the racism and divisive politics that demagogues must utilize to achieve and keep power?

It’s terrifying just how close Trump seemed to come to the White House before his latest blunders. But what would be even more terrifying is the possibility another, much more polished demagogue, might stir up the Take Back America crowd in future election cycles.

African-Americans now comprise 50 percent of our 2.3 million prison population when they are 12 percent of our population. There are many states that restrict many other rights (mainly red states), including abortion rights, immigration, even the collective bargaining rights of workers that are no longer able to negotiate for their own living wages.

Preventing another Donald Trump is why our political leaders must to find a way to re-unite the Divided States of America.

Harlan Green © 2016

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen
Posted in Economy, Politics, Uncategorized | Tagged , , , | Leave a comment

Motor Vehicle Sales Boost Retail, Manufacturing

Financial FAQs

One of the first hard indications on the September economy is strongly positive as overall unit vehicle sales surged 4.7 percent to a 17.7 million annualized rate. This will boost the vehicle component of the September retail sales report and also will give a lift to third-quarter GDP estimates, which are currently in the mid-two percent range.

image

Graph: Calculated Risk

Strength is centered in North American-made models where the rate rose 6.0 percent to 14.2 million for domestic sales. The strength ultimately reflects the health of the jobs market and will likely raise talk of strength in Friday’s employment report.

And initial weekly jobless claims keep moving lower in what is definitive evidence of labor market strength. Initial claims in the October 1 week fell 5,000 to 249,000, breaking the 250,000 barrier for the second time this year, though the unemployment rate rose slightly to 5.0 percent and 156,000 new payroll jobs were created in September, according to the Labor Dept.

The 4-week average, 2,500 lower at 253,500, is down for a very convincing 7th week in a row, says Calculated Risk. Continuing claims are likewise moving lower, down 6,000 to 2.058 million in lagging data for the September 24 week. There are no special factors in today’s report, one where all readings are at or near historic lows.

Both U.S. manufacturing and non-manufacturing activity picked up as well. largely due to the strength in vehicle sales, which means retail sales overall are healthy. ISM’s manufacturing September index bounced more than 2 points higher to a much better-than-expected 51.5. New orders are the most important of all readings and they lead the September report, rising 6 points to a very solid 55.1.

Export orders are also respectable and steady at 52.0 while the draw in total backlog orders slowed, with this index up 4 points and nearly hitting breakeven 50 at 49.5. Production also improved in the month, up 1.4 points to 52.8, as did employment which, at 49.7, is also nearly at 50. This is a positive report, pointing to rising though no more than moderate strength for the nation’s factory sector.

And the ISM non-manufacturing composite index shot up to 57.1 from August’s recovery low of 51.4 which now looks like a very odd outlier for this report which otherwise has been consistently strong this year. And new orders are especially strong, up nearly 9 points to 60.0 which points to brisk activity for other readings in the months ahead. Employment is also a very solid plus in the report, up 6.5 points to 57.2 which is the strongest rate of growth since September last year.

image

Graph: Econoday

And the third estimate of Q2 Gross Domestic Product inched up to 1.4 percent from the prior 1.2 percent estimate, but Q3 should begin to show some strength, after 7 consecutive quarters of subpar growth.

Could it reach 3 percent?  Only if the Fed doesn’t raise interest rates at all this year, as it will crimp manufacturing, which relies on lower export prices, which relies on a cheaper US dollar, which relies on the current interest rate low.

Harlan Green © 2016

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Economy, Politics, Uncategorized, Weekly Financial News | Tagged , , , | Leave a comment

Why Brexit?

Financial FAQs

Brexit, the British vote to exit the European Union, was precipitated by many factors, including Brit’s fear of loss of sovereignty due to the Schengen requirement that it open its borders to citizens of other EU countries.  And it may lead to a breakup of the Eurozone.

It was a real fear—that eastern Europeans would deprive Britons of jobs by migrating from countries whose wages were lower. Great Britain’s minimum wage is more than double that of countries such as Poland, Czech Republic, and Romania, for instance, which has meant that some 1 million immigrants from other EU countries have migrated to Great Britain seeking better paying jobs, and pushing out many blue collar Brits in the process.

image

Graph: Trading Economics

So there was good reason for the Brexit vote. Great Britain’s unemployment rate only came down to 5 percent in 2016, after hovering at 8 percent since 2008, the end of the Great Recession, largely due to misguided economic policies.

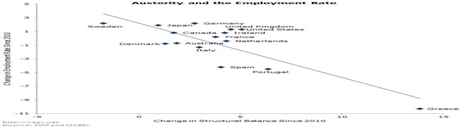
Britain’s Prime Minister David Cameron was hoisted on his own petard when he called for the referendum that precipitated Brexit, in other words. He was a strong supporter of German austerity policies that led to two recessions in most of the EU, policies that advocated cuts in government programs combined with higher taxes for Eurozone countries.

Poor job prospects in many of those countries hardest hit by the Great Recession prompted the flight to countries least affected, such as Great Britain, even though Great Britain was still suffering from job losses. The Guardian has been trumpeting this truth since Cameron’s austerity policies were instituted in the Conservative Party’s 2010 ascent to power.

“Austerity – which has affected the living standards of many working people – was not imposed by the EU, but was a choice by the current government. When public finances are tight, the economic contribution made by migrants ought to be welcomed. But the climate of cuts allowed migrants to be blamed and Britain’s contribution to the EU – at £8bn, just 1.2 percent of public expenditure and outweighed by our economic gains from membership – to take on disproportionate significance.”

Many major economists have written about the failure of austerity policies since the end of the Great Recession, including Nobelist Paul Krugman.

image

Graph: Slate.com

“Since the global turn to austerity in 2010, said Krugman in the Guardian, “every country that introduced significant austerity has seen its economy suffer, with the depth of the suffering closely related to the harshness of the austerity. In late 2012, the IMF’s chief economist, Olivier Blanchard, went so far as to issue what amounted to a mea culpa: although his organisation never bought into the notion that austerity would actually boost economic growth, the IMF now believes that it massively understated the damage that spending cuts inflict on a weak economy.”

Maybe we should also mention it is the reason why the Eurozone is in danger of breaking up, all because of not knowing how to deal with the huge amount of debt incurred during and by the Great Recession. All countries suffered, as they did after WWII. But the western world had visionary leaders then, willing to rebuild those European countries in particular with something called the Marshall Plan—some $17 billion in loans and grants—one quarter of which went to Great Britain.

It was also a time when 50 percent of German debt was forgiven—that is, cancelled. But are there any such leaders today that might help Greece and Portugal, at the very least? Unfortunately, we are instead harking back to WWI history, and the punitive demands made on Germany for war reparations that precipitated Hitler and WWII.

London School of Economics Professor of Economic History Albrecht Ritschl conducted research into how Germany was able to pay off its debts after the two World Wars. Ritschl looked in detail at the financial assistance that was paid to Germany under the Marshall Plan, in which the US gave that $17 billion – around $160 billion in today’s values – in economic support to help rebuild European economies. He showed that while the transfers were tiny, the cancellation of debts was worth as much as four times the country’s entire economic output in 1950 and laid the foundation for Germany’s fast post-war recovery.

If we had such leaders today, could it have prevented Brexit and the possible breakup of the Eurozone—and maybe the European Union, as well?

Harlan Green © 2016

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Economy, Keynesian economics, Politics, Uncategorized, Weekly Financial News | Tagged , , , , , , , , , | 1 Comment

Holiday Cheers–Consumers Feel Happier!

Popular Economics Weekly

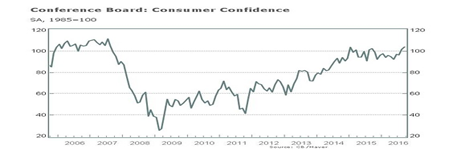
It’s back to school time, and consumers are feeling the holiday spirit already. Americans in September were most optimistic about the economy since the summer of 2007, in part because of a happier view of the U.S. labor market. And coupled with rising wages, could mean a very good holiday season for businesses.

image

The index of consumer confidence climbed to 104.1 this month from 101.8 in August, the Conference Board said Tuesday. That’s well above the 99.3 forecast of economists and it marks the highest level since August 2007, just a few months before the onset of the Great Recession.

The Conference Board says it is about better job security, but I believe rising wages are a better reason for optimism. The present situation index, a measure of current conditions, climbed to 128.5 from 125.3. That’s also the highest level since August 2007.

“Consumers’ assessment of present-day conditions improved, primarily the result of a more positive view of the labor market,” said Lynn Franco, director of economic indicators at the board. “Looking ahead, consumers are more upbeat about the short-term employment outlook, but somewhat neutral about business conditions and income prospects.”

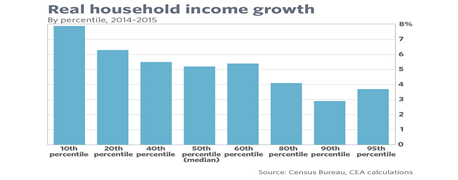
But there is also new data showing middle-class household incomes growing at the fastest rate since the recession, which seemed to confirm that a recovery is finally touching the lives of ordinary, especially middle-class Americans.

This may shake up retail sales that have also been in a summer swoon, because the largest wage growth is occurring in the lowest income brackets that have to spend most, if not all, of their incomes to maintain a decent standard of living.

image

Graph: Marketwatch

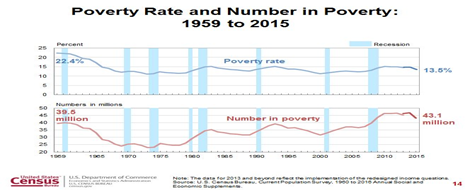
This could largely be due to the rise in the minimum wage in some large cities, of course. The official poverty rate fell 1.2 percentage points between 2014 and 2015 to 13.5 percent, and the number of people in poverty fell by 3.5 million, says the Census Bureau. The threshold for a family of two adults and two children to be considered living in poverty was $24,036. 

Rising consumer confidence is a good sign for continued economic growth, needless to say. But will it be enough to get us out of the 2 percent GDP growth rate of late? We will actually need much more, like more capital expenditures that has been cut back during the years when budget cuts were the priority, rather than productive investments.

Harlan Green © 2016

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Economy, Weekly Financial News | Tagged , , , , , , | Leave a comment

When Will (Housing) Selling Season End?

The Mortgage Corner

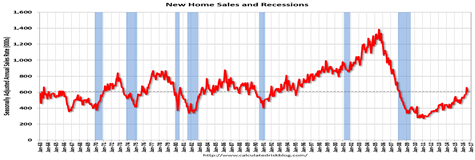
It’s already October and the housing market continues to boom—even after the kids are back in school, the usual end of the sales season. Sales of newly-constructed homes dropped 7.6 percent in August, though they beat forecasts. New home sales ran at a 609,000 seasonally adjusted annual rate, the Commerce Department said this morning. That was 20.6 percent higher compared to a year ago. And July’s number, previously reported as 654,000, was revised upward to 659,000, marking the highest total since late 2007.

image

Graph: Calculated Risk

So despite the recent softness, housing sales are still climbing, thanks in large part to Janet Yellen’s Fed, which keeps postponing the inevitable next rate hike. The real problem causing the current slowing in sales is lack of inventory.

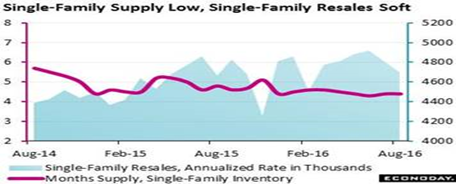
This graph compares the monthly supply of single-family homes, at 4.4 months in the last two reports, with resales of single-family homes, which came in at 4.70 million in August. When including condos, supply on a monthly basis is at 4.6 months with 3.3 percent fewer resales available, at 2.04 million from July’s 2.11 million.

image

The real strength of this year’s housing sector is on the new home side. Housing starts and permits did fall in August, down a sharp 5.4 percent for starts to a 1.142 million annualized rate and down 0.4 percent for permits to 1.139 million. But permit growth for single-family homes, which is a central indication for housing demand, bounced back 3.7 percent from a weak July to a 737,000 rate which, as seen in the red line of the graph, is about as good as it gets, says Econoday.

image

“The August reading represents a one-month blip in what has been a long-term, gradual recovery,” said NAHB Chief Economist Robert Dietz. “On a year-over-year basis, single-family starts are up 9 percent while multifamily construction continues to level off at a solid level as that sector seeks to find a balance between supply and demand.”

And prospects for ongoing strength in the new home sales report are very solid based at least on the home builders’ housing market index which is up a very sharp 6 points this month to 71, a level last matched in October last year.

So the only thing that seems to hold back housing sales is the lack of supply, as we said, and that is due to builders having problems finding construction workers in a near fully-employed economy. What could be better? The surge in new condo sales is a sign that more affordable housing is coming on line, which should help the first-timers, who comprise just 31 percent of existing-home sales at present, down from the 40 percent during more normal times.

Harlan Green © 2016

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen
Posted in Consumers, Housing, housing market, Weekly Financial News | Tagged , , , , | 1 Comment

Poverty Level Down, As Household Incomes Surge

Popular Economics Weekly

Fewer Americans lived in poverty in 2015 and median incomes charted their first increase since the Great Recession, according to data released Tuesday by the Census Department. The official poverty rate fell 1.2 percentage points between 2014 and 2015 to 13.5 percent, and the number of people in poverty fell by 3.5 million, Census said. The threshold for a family of two adults and two children to be considered living in poverty was $24,036.

image

Graph: Census Bureau

And new data showing middle-class household incomes growing at the fastest rate since the recession seemed to confirm that a recovery that’s remained slow and uneven is finally touching the lives of ordinary, especially middle-class Americans.

image

Graph: Marketwatch

In fact, this could be the income growth needed to bring US back to 3 percent GDP growth; something that hasn’t happened since before the Great Recession. Millions of Americans escaped poverty last year and incomes rose at their biggest gain ever, as the 6-year long economic recovery finally hit home for households. Median middle-class wages surged 5.2 percent between 2014 and 2015, the Census Department said Tuesday, the first annual increase since 2007, just before the economy plunged into recession.

This is in large part due to almost non-existent inflation, which has not returned to even the Fed’s 2 percent target, hence the reluctance of Janet Yellen’s Federal Reserve to raise interest rates at all this year. But that may change, as rising wages also have an effect on inflation, since wages make up some two-thirds of product costs.

An even better way to increase growth is to invest more in what would grow our economy; like infrastructure, education, R&D, the environment, etc. That’s why productivity has ground to a halt, which is the main driver of future growth.

At least 43 companies plan to cut, or leave unchanged, their capital spending levels in 2016, while about 20 are increasing, according to a Reuters review of Standard & Poor’s 500 companies that have given explicit early guidance.

image

Graph; Citibank

However, Citibank seems to disagree. It’s the energy sector that has cut back due to the slump in energy prices. This, however, is boosting growth in capex spending in other sectors, says Tobias Levkovich, Citigroup chief equity strategist. There’s no reason to think stock buybacks, the current straw man for the lack of productive investment, are replacing capital expenditures. Rather, he said, they are complementing them.

“While misperceptions abound when it comes to companies allegedly not investing in their businesses and preferring to buy back stock instead, there is little corroborating evidence,” Levkovich argued. “S&P 500 companies have had capital investment dollars ahead of the amount used for buybacks for more than four and a half years and capex has hit a record every year since 2011.”

And a major reason for this is the low cost of capital is today’s low inflationary environment. So there is good reason to keep interest rate as low as possible, until we see signs of more normal GDP growth.

Harlan Green © 2016

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen
Posted in Economy, Macro Economics, Politics, Weekly Financial News | Tagged , , , , , | Leave a comment

Why Isn’t It Easier to Qualify For A Mortgage?

The Mortgage Corner

It’s not getting any easier to obtain a mortgage. This is in spite of record low mortgage rates, as low as 3.0 percent for 30-year conforming fixed rates; as well as the appearance of so-called Alt-A, non-QM mortgages with 3 to 7 year, interest only, fixed rates that require 12 months personal bank statements to verify income.

According to a report from the Urban Institute that tracks mortgage availability among other housing issues, the pool of mortgage loans made between 2011 and 2015 have even lower default rates than the more “normal” lending period of 1999 to 2003, when less than 2 percent of the loans defaulted after 10 years.

By comparison, 12 to 13 percent of the mortgage loans made at the height of the housing bubble between 2006 and 2007 defaulted within 10 years of their origination, the Urban Institute said in August, citing Fannie Mae’s data. And that was mostly due to the Great Recession and loss of some 8 million jobs.

image

Graph: Calculated Risk/Black Knight

The Urban Institute noted that of Fannie Mae- and Freddie Mac-backed loans made after 2011 and through the first quarter of 2015, 69 percent of the borrowers had FICO scores better than 750. Between 1999 and 2003, only a third of people with such mortgages had a credit score that high. Less than 1 percent of loans that have been made after 2011 have defaulted, according to Fannie Mae’s data, the Urban Institute said, even for those borrowers with FICO scores under 700

Requiring higher credit scores is just one way lenders have made it more difficult to qualify. Fannie and Freddie also pile on points for scores above 680, which was a normal mid-score before the housing bubble, and in effect boosts the interest rate. For instance, just a 1 pt. cost add on for a score below 700 is the equivalent of a one-quarter percent raise in the rate.

Other problems are due to the reforms mandated by Dodd-Frank designed to protect consumers from predatory lenders, while a good idea, have made it much more difficult for lenders and slowed down the qualification time. This includes additional delays in closings for the slightest change in rates or points enacted due to the new TRID requirements (short for TILA/RESPA Integrated Disclosure) enacted last fall.

This has made lenders much more selective in granting mortgages. We are probably back to 1980s qualification standards when many fewer loans were granted—mostly by S&Ls that disappeared after the late 1980s banking scandals.

We are in a much better position today, 7 years after the Great Recession, in other words. The inventory of loans in negative equity positions dropped by 31 percent (1.5 million) in 2015, according to Black Knight. At a total of 3.2 million, or 6.5 percent of all homeowners with a mortgage, this represents significant improvement from the peak in 2010, but is still well above “normal” levels.

image

Graph: Black Knight

Both the S&P Case-Shiller Home Price Index and Corelogic stats show home prices rising as much as 10 and 11 percent in Portland and Seattle, respectively, in its latest 3-month averaged, same home survey, and 5-6 percent nationally on average. This will continue to bring back housing values and lower negative equity in homes.

So there’s no reason to continue to be as cautious as mortgage lenders are today. There is of course the political brouhaha over whether Fannie and Freddie should become private corporations again, and so separated from US Treasury control. With their future unclear, these entities that guarantee more than 60 percent of all mortgages make lenders doubly cautious about qualifying younger, entry-level borrowers, in particular.

Harlan Green © 2016

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen
Posted in Consumers, Economy, Housing, housing market, Politics, Weekly Financial News | Tagged , , , , , | 1 Comment

A Record In Job Openings

Financial FAQs

Not only are Nonfarm payrolls averaging some 200,000 jobs per month this year, but the Labor Department’s job openings and labor turnover survey showed 5.87 million openings, an all-time high, while hires increased to 5.23 million from 5.17 million in June. Businesses are creating jobs at a much faster rate than they can be filled, in other words.

The number of job openings are up 1 percent year-over-year. Quits are up 9 percent year-over-year. Quits are voluntary separations, which usually means workers must have found better paying jobs.

image

Graph: Econoday

The number of people quitting jobs voluntarily was flat at 2.98 million, but that’s still up substantially from the depths of the recession, which signals more worker confidence in the ability to find another job, as I said.

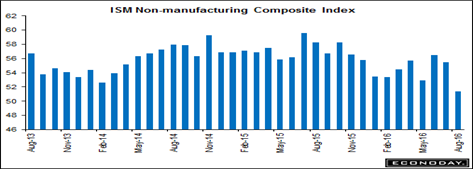
Less heartening was yesterday’s ISM’s Non-Manufacturing (i.e., service sector) survey for July, down 4 points to 51.4. This is the lowest rate of composite growth for this sample of the whole cycle since February 2010. But that may be a fluke, as new orders in past months were as high as 60 percent. It could be a catch-up month, in other words, as businesses sell off past months’ inventories.

image

Graph: Econoday

This should also keep the Fed from raising interest rates until at least December, since the jobs report of last week was a letdown, as well. The composite score is no fluke, says Econoday, with new orders for service sector products falling nearly 9 points to 51.4 for their lowest score since December 2013. New export orders are a particular disappointment, also down a steep 9 points and in contraction at 46.5 which is also the lowest score since December 2013. And backlog orders are also in contraction, down 1-1/2 points to 49.5.

Moody’s doesn’t see this lull as more than a blip, at least. The U.S.’s Aaa credit rating is safe no matter who wins the presidential election, according to Moody’s Investors Service in a new report on Wednesday.

“The outcome of the forthcoming presidential election will not impact the Aaa stable credit rating of the United States, regardless whether Donald Trump or Hillary Clinton is elected,” the report says. “This is because the U.S.’s rating reflects the country’s very high degree of economic, institutional and government financial strength and its very low susceptibility to event risk,” says Moody’s, naming the four factors in its sovereign bond rating methodology.

What to make of the current weakness? It could be a summer lull, as businesses wait for the results of Brexit negotiations, the Presidential election, and maybe even China’s growth to resume.

Harlan Green © 2016

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen
Posted in Economy, Macro Economics, Politics, Weekly Financial News | Tagged , , , | Leave a comment