Mortgage Delinquency and Foreclosure Rates Lowest Since 2007

The Mortgage Corner

The delinquency rate for mortgage loans on one-to-four-unit residential properties decreased to a seasonally adjusted rate of 5.85 percent of all loans outstanding at the end of the third quarter of 2014. This is approaching the historical average of 4.25 percent with those eastern and Midwestern states that conduct judicial foreclosures lagging the mostly western states that conduct Trust Deed auctions in clearing their books of delinquent loans.

The delinquency rate decreased for the sixth consecutive quarter and reached the lowest level since the fourth quarter of 2007. Whereas the delinquency rates for Fannie Mae and Freddie Mac are even lower—2.05 percent for “seriously delinquent” mortgages more than 90 days late in payments.

image

Graph: Calculated Risk

So it is another sign of the housing recovery. All areas of distress are lower, and housing prices continue to rise, though more slowly than last year. Housing price for homes with Fannie Mae guaranteed loans are up 5.9 percent YoY, and 6.1 percent for Freddie Mac guaranteed loans.

“Delinquency rates and the percentage of loans in foreclosure fell to their lowest levels since 2007,” said Mike Fratantoni, MBA’s chief economist. “We are now back to pre-crisis levels for most measures. Foreclosure starts were unchanged on a seasonally adjusted basis, but increased slightly in the raw data. Given that this measure reached the lowest level in eight years last quarter, and given the continued decline in delinquency and foreclosure inventory rates, we expect that the increase in the unadjusted starts rate is just regular seasonal fluctuation.”

The problem is mainly in the eastern states that have judicial foreclosures which must be processed through the courts, which is a very time-consuming process. For instance, Nevada is the only non-judicial state in the top 10, and this is partially due to state laws that slow foreclosures (D.C added some new foreclosure mediation requirements).

The top states are New Jersey (7.96 percent in foreclosure, down from 8.10 percent in Q2), Florida (6.12 percent), New York (5.72 percent) and Maine (4.29 percent).  Former bubble states California (1.05 percent) and Arizona (0.85 percent) are now far below the national average by every measure.

image

Graph: Calculated Risk

This graph that dates from 2006 shows the difference. The blue line charts Judicial foreclosures (blue line) down to 4.20 percent of inventories, while Non-judicial foreclosures (dotted blue line) have fallen to 1.27 percent on inventories.

And interest rates are back to historical lows with ultra-low inflation. Thirty-year conforming fixed rates are now 3.75 percent in California, for instance. And such low inflation could be around for years to come, as there is oversupply in most commodities, including oil, that is feeding the deflationary environment.

This is good news for the housing market and real estate in general, as it makes housing more affordable for even entry-level buyers who have been priced out of the housing market during this recovery.

Harlan Green © 2014

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Housing, housing market, Weekly Financial News | Tagged , , , , , , | Leave a comment

Retail Sales, Consumer Sentiment Boosting Holiday Cheer

Popular Economics Weekly

Retail Sales are growing again, and U. of Michigan survey of consumer sentiment is also spiking at the right time of year for holiday sales. That’s because job openings and hires in the September JOLTS report are bringing US closer to full employment. This is especially in some high growth areas of the country, such as California’s Silicon Valley, where unemployment rates have dropped to the low 4 percent range in September.

image

Graph: Calculated Risk

Retail sales ex-gasoline surged by 5.1 percent on a Year-over-Year basis–4.1 percent for all retail sales—which is somewhat misleading because sales aren’t adjusted for inflation, which has been falling. Retail outlets now routinely offer 20 percent discounts for goods of all kinds, except for luxury goods, due to depressed household incomes. So sales volumes’ have probably been rising faster than the indicators.

Fallen incomes have been the overall problem, and the reason for the slow recovery, since lower incomes depress prices which leads to decreased demand for those goods and services. But the latest JOLTS report is heartening. There were 4.7 million job openings on the last business day of September, barely changed from 4.9 million in August, but the Quits and Hiring levels are surging.

Quits are generally voluntary separations initiated by the employee. Therefore, the quits rate can serve as a measure of workers’ willingness or ability to leave jobs, and is a major employment  indicator liked by Fed Chairman Janet Yellen. The number of quits increased from 2.5 million in August to 2.8 million in September. This was the highest level of quits since April 2008. And companies hired 5.03 million people in September, which is the highest number since December 2007, just as the Great Recession started.

The following graph from Calculated Risk shows job openings (yellow line), hires (dark blue), Layoff, Discharges and other (red column), and Quits (light blue column) from the JOLTS.

image

Lastly, the preliminary Reuters / University of Michigan consumer sentiment index for November was at 89.4, up from 86.9 in October. This was above the consensus forecast of 87.5 and is at the highest level since 2007 in this graph that dates back to 1980.  So we can see that it has yet to climb above 90 to reach sentiment that prevailed during full employment periods that prevailed especially during the 1990s.

image

Graph: Calculated Risk

So once again, we are seeing the Goldilocks economy at work. It’s not running too hot (high inflation), or too low (there is good job creation). It is household incomes that need to rise, which should happen as we creep towards full employment. Full employment won’t be reached until the unemployment rate is in the 4 percent range these days, given the 11.1 million in underemployed and unemployed workers looking for work or wanting full time jobs.

That’s why most economists aren’t predicting that full employment will be achieved until sometime in 2016.  Guess what else is happening in 2016!

Harlan Green © 2014

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Economy, Keynesian economics, Weekly Financial News | Tagged , , , , , | Leave a comment

California’s Budget Surplus Leads to Credit Upgrade

Popular Economics Weekly

A day after voters passed Proposition 2, which creates a “rainy day fund” to cushion the state budget from future economic downturns, major credit-rating house Standard & Poor’s on Wednesday upgraded California’s general obligation bond rating. S&P raised the state’s credit rating from A to A-plus, citing the stability offered by Proposition 2.

But it’s more than that. California’s unemployment rate dropped to 6.8 percent in September, according to the State Unemployment Office and the U.S. Bureau of Labor Statistics. The San Francisco Bay area led the way with San Francisco and the surrounding counties’ jobless rates in the low 4 percent, which in essence means full employment.

Proposition 2, championed by Gov. Jerry Brown and passed by the Legislature on a bipartisan vote, requires the state to set aside funds, especially when revenue from taxes on capital gains is high, to both pay down debt and create a reserve that can be tapped only when the state is in fiscal distress.

What happened to the California economy that several years ago was pronounced dead or dying by its critics, conservatives determined to downsize government with budget and tax cuts to punish everyone, except the wealthiest? Governor Jerry Brown did just the opposite—raised more revenues to stimulate job growth, at a time of record low interest rates, as the S&P upgrade noted.

Californians won the battle of economic ideologies that has blocked so much growth in the rest of the country; such as with Kansas, the poster child for cutting government programs that has set its economy in reverse.

“The upgrades follow voter approval on Nov. 4, 2014, of a strengthened budget stabilization account under Proposition 2,” S&P analyst David Hitchcock said in a statement. “In our view, the new state constitutional provision will partially mitigate California’s volatile revenue structure by setting aside windfall revenue for use during periods when state tax revenue could fall materially short of forecast.”

And California now has a very large budget surplus, because of it. State Controller John Chiang in a press release just released his monthly cash report for the month of June, and announced that the state’s General Fund — the primary account from which California funds its day-to-day operations and programs — ended the fiscal year with a positive cash balance for the first time since June 30, 2007.

A positive cash balance means that the state had funds available to meet all of its payment obligations without needing to borrow from Wall Street or the $23.8 billion available in its more than 700 internal special funds and accounts.

And what about California’s drought could badly hurt future growth? Voters also overwhelming approved Proposition 1 was to address water conservation and climate change problems that could create even more severe water shortages in the future.

"At its core, Proposition 1 advances an all-of-the-above strategy that includes everything from local resources to water storage to safe drinking water," said Timothy Quinn, executive director of the statewide Association of California Water Agencies. "Other states facing similar challenges may learn from that approach."

And that is the point. California, once thought the economic basket case, has instead become the model that both red and blue states should follow.

Harlan Green © 2014

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Economy, Keynesian economics, Politics, Weekly Financial News | Tagged , , , , , | Leave a comment

Jobless Rate Falls to 5.8 Percent—Why be unhappy?

Financial FAQs Weekly

Nonfarm payroll jobs advanced 214,000 in October after gaining 256,000 September and 203,000 in August. Net revisions for August and September were up 31,000. The unemployment rate dipped to 5.8 percent in October from 5.9 percent in September. So why were voters Tuesday so pessimistic about the economy and jobs?

image

Graph: Marketwatch

Job creation in October marked the ninth straight month the economy has added 200,000 jobs or more, a feat last accomplished in 1994. The U.S. has created some 2.3 million jobs this year and is on track for the biggest gain in almost a decade. What’s more, job openings recently hit a 13-year high while layoffs have fallen to the lowest level since the turn of the century, says Marketwatch.

The unemployment rate, meanwhile, fell again as more than half a million people found work, according to a survey of households. And another 400,000-plus joined the labor force, a good sign because it means people think more jobs are available.

But wages are still rising 2 percent per year, which is just keeping up with inflation. And the U-6 measure of so-called underemployed is still 11 percent, which includes not just those who are unemployed, but those who are “marginally attached” to the workforce as well as those who want a full-time job but can only work a part-time job.

These are some of the reasons that voters were unhappy at last Tuesday’s election. Exit polls after Tuesday’s midterm elections showed that just one-third of Americans think the economy is getting better, and an even larger number believe the U.S. is headed in the wrong direction.

Goods-producing jobs increased 28,000 in October after a 36,000 gain the month before. Manufacturing employment increased 15,000 in October, following a rise of 9,000 in September. Motor vehicles and parts rebounded 3,000, after slipping 1,000 the month before. Construction advanced 12,000 after a gain of 19,000 in September. Mining edged up 1,000 in October, following an 8,000 rise in September.private service-providing jobs gained 181,000 after a 208,000 boost in September. Strength again was seen in professional & business services and retail trade.

The question is why when several times since the 2009 end of the Great Recession, Republican anti-government policies almost drove us back into recession. In 2011, Republicans took the government to the brink of default on its debt (and S&P downgrade of U.S.) , which led to an agreement with Obama, Harry Reid and Nancy Pelosi to cut spending, by automatically sequestering funds if necessary.

A year ago, the Republicans again forced the issue with a 16-day partial shutdown of the federal government, which led to another agreement with the Democrats on spending cuts.

So now that they control both the House and Senate, and new Senate Majority Lead Mitch McConnell says they will no longer be shutting down government, they will have to find a way to work with the Democrats to lose their ‘no compromise’ past.

The problem is Republicans have been wrong on every economic issue that would improve lives—from budget deficits to health care, from tax cuts to public infrastructure spending, environmental safeguards, Dodd-Frank financial regulation; not to speak of their war on contraception, voters’ rights, and collective bargaining that would raise workers’ income—you name it.

They have literally been wrong on every issue that keeps this economy afloat. It is an abysmal record of economic ignorance. How will they change their ways?

Harlan Green © 2014

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Economy, Politics, Weekly Financial News | Tagged , , , , , , | Leave a comment

Bullies, Not Government Is the Problem

Financial FAQs Weekly

Even though the U.S. economy grew by a 3.5 percent annual rate in the third quarter, boosted by a surge in exports and the biggest jump in federal spending in five years, Democrats don’t seem to be taking credit for it.

Why? The bullies are in control, whether they are Republican Tea Partiers that refuse to compromise on any legislation that won’t downsize government programs, the Koch Brothers who fund any candidate or cause that cuts environment regulations, or the NRA, lobbying arm of the gun industry that capitalizes on gun violence to boost weapons sales; they control Washington’s agenda these days.

And it has almost wrecked our economy several times since the 2009 end of the Great Recession. Republicans dare not take credit for it, either. “Anyone who trusts the Republicans hasn’t been paying attention to what their economic policies have been. Instead of focusing on full employment and higher wages, the Republicans have doubled down on the trickle-down policies that have failed so miserably over the past 30-plus years,” says Marketwatch economist Rex Nutting.

In fact, several times since the 2009 end of the Great Recession, Republican anti-government policies almost drove us back into recession. In 2011, Republicans took the government to the brink of default on its debt (and S&P downgrade of U.S.) , which led to an agreement with Obama, Harry Reid and Nancy Pelosi to cut spending, by automatically sequestering funds if necessary.

A year ago, the Republicans again forced the issue with a 16-day partial shutdown of the federal government, which led to another agreement with the Democrats on spending cuts.

Why do we call them bullies? Because they have been able to get away with it. And because it looks like Republicans might gain control of the Senate, it’s Democrats who have been willing to compromise, when their economic agenda has brought the unemployment rate down to 5.9 percent, and economic growth above 3 percent over the last 2 quarters.

The problem with dealing with such bullies that say it’s ‘my way or the highway’, is that they take any sign of compromise as a sign of weakness. So when Vice President Biden says, ““[L]ook, we’re — we’re ready to compromise,” bullies see it as a sign of weakness, that they have already won the battle of this midterm election, so there is no need to compromise.

“Going into 2016, the Republicans have to make a decision whether they’re in control or not in control,” the vice president told CNN’s Gloria Borger. “Are they going to begin to allow things to happen? Or are they going to continue to be obstructionists? And I think they’re going to choose to get things done.”

Unfortunately, that is not how to deal with the bully mentality that has pervaded much of today’s politics, as well as our schools. It only happens when there is a leadership vacuum, when strong leaders refuse to step forward that know how to oppose bullies. Yet we know how–history has told US. That’s how we defeated the biggest bullies of all; Hitler and Emperor Hirohito, and even Stalin. Just stand up to them, and only compromise when the bullies are willing to compromise.

Harlan Green © 2014

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Economy, Macro Economics, Politics, Weekly Financial News | Tagged , , , , , , , , , , , , , | Leave a comment

Government Spending Boosts Q3 GDP

Popular Economics Weekly

WASHINGTON (MarketWatch) — The U.S. economy grew by a 3.5 percent annual rate in the third quarter, fueled by a surge in exports and the biggest jump in federal spending in five years, screamed one headline this morning.

That is all we need to know to understand why US economic growth is finally returning to the long term average that has prevailed since the Great Depression. This is in spite of the Great Recession and a busted housing bubble that is taking years to recover, record wealth inequality that has kept consumers from spending, and ultra-conservative House Republicans that have refused to allow even the most basic public works spending; such as to repair and replace the roads and bridges that have so fallen into disrepair, not to speak of keeping up with the educational needs of a growing population.

image

Graph: Calculated Risk

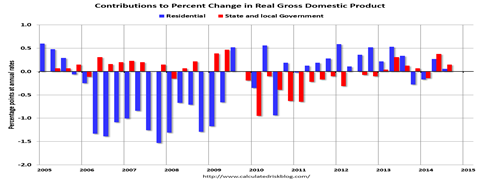
This first graph from Calculated Risk shows the increasing contribution to GDP for residential investment (RI) and state and local governments since 2005. It’s the beginning of recovery from the huge slump in RI during the housing bust (blue), followed by the unprecedented period of state and local austerity (red) not seen since the Depression.

It doesn’t tell the whole story, of course, as continuing austerity policies that cut government spending and some taxes in Japan and Europe have kept them in recession, whereas the pro-growth actions of the Fed (and boosting of some taxes) have reduced the budget deficit and kept the US government solvent.

It is a phenomenal recovery, even a miracle that this could even happen with a Congress locked in a battle over ideologies, and race. So it is thanks mainly to Ben Bernanke and Janet Yellen’s Federal Reserve QE actions, in particular, part of their pro-growth policies that pushed interest rates (especially long term rates) to record lows, just because the Fed could act outside of politics as usual.

“What’s more, the U.S. is adding jobs at the fastest rate since the recession ended in 2009 and consumers are feeling the most confidence in seven years, buoyed by a rising stock market and falling gasoline prices. As a result, most analysts believe the U.S. is likely to expand at a 3 percent pace or so in the fourth quarter to string together the best stretch of economic growth since before the Great Recession,” said the MarketWatch announcement.

So government spending was the largest contributor, up 10 percent mostly for defense, and exports up 7.8 percent annually. State and local governments’ spending rose 1.3 percent, and consumer spending slowed to a 1.8 percent annual pace from 2.5 percent in the prior quarter.

Business investment on equipment decelerated from the second quarter’s 11.2 percent gain to 7.2 percent, but is still strong. Residential housing investment grew at a low 1.8 percent rate after an 8.8 percent increase in the spring.

What does all this data mean? That there are ways around Congressional gridlock, if the executive branch and Federal Reserve concentrate on pro-growth policies that keep interest rates low, raise taxes sufficiently to lower the budget deficit, lower health care costs, support collective bargaining of employees, as well as lobby for higher household incomes to boost consumer spending (and the housing market).

And best of all, this happened with very low inflation, in spite of warnings that more government spending and the Fed’s QE policies would cause soaring inflation. Instead inflation as measured by the PCE index rose just 1.2 percent annually, down from 2.3 percent in Q2, as cheaper energy prices has kept inflation ultra-low. Even the core PCE that excludes food and energy rose just 1.4 percent.

We can now say officially that we have that goldilocks economy that prevailed through the 1990s; not too hot or too cold that will boost economic growth for years to come, if Congress can be ignored.

Harlan Green © 2014

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Economy, Housing, housing market, Politics, Weekly Financial News | Tagged , , , , , , , | Leave a comment

Consumer Confidence Soaring, Case-Shiller Home Prices Unchanged

Popular Economics Weekly

Why are stock prices rallying?  Maybe it’s because though housing price increases have slowed, consumer confidence is soaring for the holidays.  The prospect for future job and income growth looks good, in other words

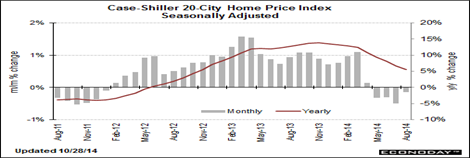
Home prices contracted for a 4th straight month in August in Case-Shiller 20-city data, down 0.1 percent vs expectations for a gain of 0.1 percent. This is while consumer confidence rose to a post-recession high, a good sign for increased holiday spending.

Month-to-month prices declined in just 3 of the 20 cities, monthly—Charlotte, NC, San Diego, and San Francisco—with San Francisco, Las Vegas and Miami prices up the most year-over-year.

So though the 20-city monthly average fell sharply, annual year-on-year overall prices are still a plus 5.6 percent from plus 6.7 and 8.0 percent in the two prior months for the 20-city index. The 5.6 percent rate is the lowest since November, says Econoday.

image

Graph: Econoday

This is while the Conference Board’s Consumer Confidence Index for October is at a new recovery high of 94.5, up from an upwardly revised 89.0 in September and surpassing the previous recovery high of 93.4 in August. The last time the index reached this level was in October 2007, right at the beginning of the Great Recession.

image

Graph: Econoday

October’s gain is concentrated almost entirely in the expectations component, which jumped 8.6 points to 95.0 in a reading that is close to February 2011’s 97.5. The strength in expectations reflects optimism in the outlook for both jobs and income, both of which show convincing gains in this month’s report.

Despite improved housing conditions and low interest rates (as low as 3.625 percent for the conforming 30-yr fixed rate today), tight credit conditions continue to be a barrier for some buyers, as we have said in past columns. Of the reasons for not closing a sale, about 15 percent of Realtors in September reported having clients who could not obtain financing, reports the NAR.

image

Graph: Calculated Risk

Lastly, the so-called price-to-rent ratio tells us that prices are again rising faster than rents, and are above the long term ratio of 1:1. This means that housing prices are growing faster than rents again. Ergo, prices cannot continue this trend for long, since rent increases mirror actual income increases, whereas prices rise or fall for a number of reasons. This includes the perception that housing prices will continue to rise (due to irrational exuberance, which is an early sign of housing inflation) and perhaps ultra-low interest rates, which must eventually rise to more normal levels.

On a price-to-rent basis, the Case-Shiller National index is back to February 2003 levels, the Composite 20 index is back to September 2002 levels, and the CoreLogic index is back to July 2003, reports Calculated Risk.

So are we at the beginning of another housing bubble? Probably not, because the main cause of the current price increases is inadequate new home construction to meet the demand for housing (which is rental housing, at the moment), rather than oversupply of new homes that caused the housing bubble to burst.

Harlan Green © 2014

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Economy, Housing, housing market, Weekly Financial News | Tagged , , , , , | Leave a comment

NRA Uses Gun Violence to Maximize Profits

Financial FAQs

How can we believe the National Rifle Association opposes gun violence when every mass murder committed with guns is answered by the NRA’s call to buy more weapons? There have been 3 mass killings by crazed gunmen just over the past week, and the gun industry’s reponse via the NRA is that guns don’t kill people, people kill people.

The latest attempt by the gun industry to boost sales is to compete with a Washington State ballot initiative that limits gun sales. Initiative 594 would require universal background checks, whereas their Initiative 591 bars universal background checks. Guess which one is backed by the gun industry? So restricting gun sales via universal background checks won’t stop the killers? Really?

It means those gun makers who fund the NRA are directly responsible for the bizarre mass shootings that have discriminately killed so many children and adults. Their only answer has been to blame the victims who hadn’t purchased guns (with high capacity magazines) for not being ‘cocked and ready’ when a crazed gunman commits mayhem.

Yet large capacity ammunition magazines are the common thread uniting all of the high-profile mass shootings in America, according to the Washington DC Violence Policy Center that listed the mind-numbing results—42 mass killings from 1984 to June 2013, with 380 killed and 365 wounded by the gunmen. Two of the shooters used assault rifles with 75-round high capacity drum magazines enabling the huge body count.

The shooter who killed 20 children and 7 adults at Sandy Hook Elementary School in Newtown, Connecticut in 2012 equipped his assault weapon with 30-round magazines, which enabled him to fire 154 rounds in less than five minutes.

The gunman in Tucson, Arizona who killed six people and injured 13 others, including U.S. Representative Gabrielle Giffords, in a supermarket parking lot in 2011, used a handgun equipped with a 33-round magazine.  His shooting spree was only interrupted when he was tackled by a bystander as he finally stopped to reload his weapon.

We have to look at when gun manufacturers began to manufacture large magazine weapons in order to increase their profits for the origins of the mass killings. In fact, prior to the 1980s, the most popular type of handgun was the revolver, which typically holds six rounds of ammunition in a rotating cylinder. During the 1980s, however, the firearms industry began mass producing and marketing semiautomatic pistols, which can accept ammunition magazines.

In 1980, semiautomatic pistols accounted for only 32 percent of the 2.3 million handguns produced in America.9 By 2008, however, such pistols accounted for 76 percent of the 1.8 million handguns produced that year.

How has the gun industry been able to fool so many people for so long on the facts of gun violence? Factcheck.org points out how the NRA’s reflex response to any gun violence is to mount truly bizarre campaigns that deny any culpability for the mayhem.

The NRA’s response to the Sandy Hook Elementary School killing of 20 children and 7 adults is but one example. "We need to have every single school in America immediately deploy a protection program proven to work — and by that I mean armed security," said the NRA’s Wayne LaPierre just one week after the massacre.

Why would the NRA so blatantly ignore the revulsion felt by so many over the massacre? New Jersey Governor Chris Christy highlighted the callous absurdity of Wayne Lapierre’s response. “In general I don’t think that the solution to safety in schools is putting an armed guard because for it to be really effective in my view, from a law enforcement perspective, you have to have an armed guard at every classroom,” he said. “Because if you just have an armed guard at the front door then what if this guy had gone around to the side door? There’s many doors in and out of schools.”

So the gun industry would be much happier it they could sell every teacher a firearm that would have to be kept in every classroom to be an effective deterrent. That would really boost their profits!

The Sandy Hook massacre even caused the U.S. Senate to attempt to take action to tighten gun regulations with universal background checks, including for gun show and online sales. Yet it was still voted down because of a multi-million dollar lobbying campaign by the gun industry.

“I agree wholeheartedly with the goal of the NRA,” Joe Manchin, one of the bill’s sponsors. “I was surprised when the latest alert from the NRA was full of misinformation. … They are telling members that our legislation would criminalize the private transfer of firearms by honest, law-abiding citizens. … That is a lie.”

The Brady Campaign To Prevent Gun Violence spells out the loopholes that allow gun sales to grow and gun companies to make even more profits. Online and gun show sales require no background checks, even though the Bureau of Tobacco and Firearms documents U.S. gun shows as a major source of bulk weapons’ sales to Mexican Drug Cartels.

The NRA’s excuses for Elliot Rogers Isla Vista, California, mass murder was that it was the result of California’s stringent gun regulation that prevents lawful citizens from owning guns. But that is an outright lie, as the California law only bans assault rifles with large magazine clips. California has banned the sale of Semi-automatic firearms that the state has classified as assault weapons, .50 BMG caliber rifles, and magazines that can hold more than ten rounds of

Since 2005, the gun industry and its corporate allies have given between $20 million and $52.6 million to the NRA through the NRA Ring of Freedom sponsor program. Donors include firearm companies like Midway USA, Springfield Armory Inc, Pierce Bullet Seal Target Systems, and Beretta USA Corporation. Other supporters from the gun industry include Cabala’s, Sturm Rugar & Co, and Smith & Wesson.

And industry profits have soared. According to the Christian Science Monitor, $6 billion in estimated revenue was earned by the US gun and ammunition manufacturing industry in 2012, according to a financial report by the research firm D&B First Research based in Austin, Texas. The major manufacturers include Browning Arms, Freedom Group, Olin, Aliant Tech Systems, Sturm, Ruger & Company, and Smith & Wesson.  The biggest companies are Ruger and Smith & Wesson, which represent about 30 percent of the industry.

The estimated number of guns in circulation in the United States as of 2009 was 310 million, according to a survey from the National Institute of Justice. That number includes 114 million handguns, 110 million rifles, and 82 million shotguns. The number of available guns has increased 62 percent since 1994, when there were about 192 million firearms in circulation. "Per capita, the civilian gun stock has roughly doubled since 1968, from one gun per every two persons to one gun per person," according to a report from the Congressional Research Service.

Need we say more to uncover the tactics used by gun manufactures to increase their profits, regardless of public safety concerns? The Brady Campaign’s numbers tell it all:

  • One in three people in the U.S. know someone who has been shot.
  • On average, 32 Americans are murdered with guns every day and 140 are treated for a gun assault in an emergency room.
  • Every day on average, 51 people kill themselves with a firearm, and 45 people are shot or killed in an accident with a gun.
  • The U.S. firearm homicide rate is 20 times higher than the combined rates of 22 countries that are our peers in wealth and population.
  • A gun in the home is 22 times more likely to be used to kill or injure in a domestic homicide, suicide, or unintentional shooting than to be used in self-defense.

Gun manufacturers and the NRA are maximizing profits at the expense of public safety. They have become in fact a danger to civil society, rather than protector of public safety.

Harlan Green © 2014

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Economy, Politics | Tagged , , , , , , , | Leave a comment

Pending and New-Home Sales Looking Up

The Mortgage Corner

Sales of new single-family houses are barely budging from their recession lows. But pending home sales for September nudged up to the highest this year, which is a sign that record low interest rates are bringing buyers back into the market.

Pending sales rose slightly in September and are now above year-over-year levels for the first time in 11 months, according to the National Association of Realtors.

The Pending Home Sales Index inched 0.3 percent to 105.0 in September from 104.7 in August, and is now 1.0 percent higher than September 2013 (104.0). The index is above 100 for the fifth consecutive month and is at the second-highest level since last September, reports the National Association of Realtors.

Lawrence Yun, NAR chief economist, says moderating price growth and sustained inventory levels are keeping conditions favorable for buyers. “Housing supply for existing homes was up in September 6 percent from a year ago, which is preventing prices from rising at the accelerated clip seen earlier this year,” he said. “Additionally, the current spectacularly low mortgage rates should help more buyers reach the market.”

Despite improved housing conditions and low interest rates (as low as 3.625 percent for the conforming 30-yr fixed rate today), tight credit conditions continue to be a barrier for some buyers. Of the reasons for not closing a sale, about 15 percent of Realtors in September reported having clients who could not obtain financing as the reason for not closing.

Yun says the final rule on Qualified Residential Mortgages should improve access to credit once it goes into effect next year. “The rule provides clarity for lenders and is a win for creditworthy consumers by ensuring they continue to have access to safe and affordable loan products without overly burdensome down payment requirements,” he said.

And Mel Watt, the newly appointed Director of FHFA that oversees Fannie Mae and Freddie Mac just announced he would be easing credit standards for the largest guarantors of residential mortgages.

But it is a two-edged sword, according to pundits. Watt said that Fannie and Freddie are working to develop “sensible and responsible” guidelines that will allow them to buy mortgages with down payments as low as 3 percent, instead of the 5 percent minimum that both institutions currently require. But lenders will not have to retain earnings to cover any losses, which means they could again begin to offer subprime mortgages (but that are not sold to Fannie or Freddie).

This change would apply to a “targeted segment of creditworthy borrowers” and take into account “compensating factors,” Watt said. (Housing experts speculate that maybe the lower down payments would only be offered to first-time buyers.) More details to come in the weeks ahead, Watt added.

But these provisions should boost sales to first time homebuyers, in particular who might not be able to afford larger down payments.

new sales

Graph:Calculated Risk

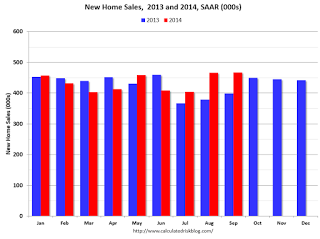
Sales of newly built, single-family homes inched up 0.2 percent in September to a seasonally adjusted annual rate of 467,000 units, the highest level in six years. Sales numbers for August were revised down from 504,000 to 466,000.

“Three consecutive months of sales upticks demonstrate steady growth in the housing market,” said Kevin Kelly, chairman of the National Association of Home Builders (NAHB). “Consistent job creation and low mortgage interest rates are spurring the release of pent-up consumer demand.”

So new-home sales have to improve, as well, to enlarge the housing inventory. Right now, most housing construction is now multi-family dwellings to absorb the increasing demand for rental housing.

Harlan Green © 2014

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Housing, housing market, Weekly Financial News | Tagged , , , , , | Leave a comment

The Mystery of Money: Understanding the Modern Financial World

Harlan Green “Unpacks” the Money Metaphor–Book Review by Mark Whitehurst / CASA MAGAZINE

Yelling “Show me the money!” usually only works in the movies, but Harlan Green’s down to earth book, The Mystery of Money: Understanding the Modern Financial World, recently published by Publishing by the Seas, Inc., opens new doors into how the realm of money really works.

Creating perspectives on how money functions and doesn’t function is what local author and columnist Green accomplishes with this book, which is a quick and easy read at 85 pages.

“Demystifying financial information for readers has always been my goal over the past thirteen years amid the breathtaking real estate and credit bubbles that have transformed both domestic and world financial markets,” writes Green in The Mystery of Money’s introduction.

Over the years, Green has been a financial columnist for The Huffington Post; Popular Economics Weekly; CASA Magazine; and the Santa Barbara News Press.

Using common knowledge and experiences that were the result of the Great Recession and the Subprime Debacle as a starting point, Green provides readers with a social connection to money. It’s a connection that continues to be disconcerting, and Green tells it like it is.

“The shocking truth was that much of the so-called ‘complexity’ was caused by willful obfuscation — the disguising of financial information via many exotic derivatives and insurance vehicles that were off the glance sheets of financial institutions,” Green explains.

Green’s explanations lead to key points of reference and how to negotiate and mediate definitions and ideas about money.

He literally opens up a discussion on the art of negotiation, using some of his personal experiences as a mortgage broker.

“The one Golden Rule of any negotiation is never to feel rushed into making a decision,” he comments.

Green moves through the classic view of Herd behavior; Imperfect Financial Markets; Decision-Making; Irrational Exuberance; Managing Big Data; Personality Cults and Charismatic CEOs; and the Mystery of Real Wealth in nine chapters and an introduction.

The book, The Mystery of Money: Understanding the Modern Financial World, will soon be available at local book stores and is available from Amazon.

Posted in Consumers, Keynesian economics, Macro Economics | Tagged , , , , | Leave a comment