
Inequality and Recessions

Has greater income equality in the United States since the 1970s, as documented by Thomas Piketty and Emmanuel Saez; (Feb. 2003 Quarterly Journal of Economics), led to greater financial instability of the financial markets, and perhaps precipitated the ‘Great Recession’ of December 2007 we are just now recovering from?

The Center for Budget and Policy Priorities (CBPP), using Piketty and Saez data, documents that income and asset inequality since the 1970s has risen to levels last seen in the 1920s (see graphs).
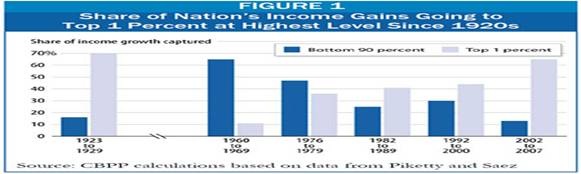
clip_image002

clip_image004

The amount such inequality contributes to recessions has not been well documented. Birdsall, Pinckney, and Sabot in a March 1996 Inter-American development Bank Working Paper 327 maintain that higher levels of income inequality “appear to be a constraint on growth”. But there has been no research on what level of inequality might lead to two consecutive quarters of negative GDP, the common definition of a recession.

This debate goes back to the Great Depression, when Roosevelt’s Federal Reserve Chairman Martin Eccles maintained that income inequality was a major cause of the Great Depression:

“… a giant suction pump had by 1929-30 drawn into a few hands an increasing portion of currently produced wealth. This served them as capital accumulations. But by taking purchasing power out of the hands of mass consumers, the savers denied to themselves the kind of effective demand (my italics) for their products that would justify a reinvestment of their capital accumulations in new plants. In consequence, as in a poker game where the chips were concentrated in fewer and fewer hands, the other fellows could stay in the game only by borrowing. When their credit ran out, the game stopped.”

By effective demand, Eccles was referring to what economists today define as aggregate demand. Eccles was maintaining that the growth in income inequality created a credit bubble that burst and so led to diminishment in aggregate demand, which economists express as a formula:
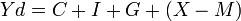
clip_image006

where aggregate demand (Yd) is the sum of all personal consumption (C) + private investment (I) + government expenditures (G) + any net of exports over imports (X-M). There was a precipitous drop in all 4 components of aggregate demand at the beginning of the Depression. Consumers in particular cut back spending 10 percent by mid-1930, in response to their stock market losses and reluctance to add new debt.

It was JM Keynes who tied aggregate demand to aggregate output, and Robert Samuelson who refined it: “The equilibrium level of output is potentially any level up to the full employment level. Which level of output actually happens to be the equilibrium depends entirely upon aggregate demand – hence aggregate demand is the primary determinant of the equilibrium level of output. This is indisputably the central message of Keynes’s theory: given any level of aggregate demand, producers will try to meet that demand and thus aggregate output will rise or fall to equate the given aggregate demand.”

Murat Iyigun and Ann Owen in the April 2004 issue of Economic Journal, “Income Inequality, Financial Development and Macroeconomic Fluctuations” maintain that in more developed economies, an increase in inequality means that there are more poor households, and so a decrease in aggregate demand.

Because poor households do not have the same ability to borrow as the rich, when they fall on hard times, they must reduce their spending, say Iyigun and Owen. Rich households, however, are able to borrow and do not have to reduce their consumption when their income is temporarily low. As a result, when there are more poor people in an economy, consumer spending will be more variable. Because consumption accounts for such a large portion of GDP (or national income), more variable consumption leads to greater GDP volatility as well.

Iyigun and Owen’s conclusion is that “the distribution of income can affect an economy’s ability to adapt to external shocks when the ability to obtain credit depends on income”.

The Great Recession of December 2007 began with such a shock—the collapse of the housing market. It precipitated a sharp drop in consumer spending, and so caused the plunge in GDP growth. This led to a “bank panic”, according to Yale economist Gary Gorton.

In a February 20, 2010 report to the U.S. Financial Crisis Inquiry Commission, Professor Gorton maintained that our most serious financial crises of the nineteenth and twentieth centuries were caused by bank panics. Whereas the 1929-30 panic was due to a run on bank deposits (due to a lack of deposit insurance), the current bank panic began on August 9, 2007 in the unregulated ‘repo’ market for sale and repurchase agreements, conducted within the highly leveraged ‘shadow’ banking system of non-bank financial entities that had escaped regulators’ scrutiny.

The discovery of links between income inequality and recessions may therefore lie in more historical research that measures the factors that lead to extreme volatility in aggregate demand. The large increase in income inequality that happened since 2000 in conjunction with the housing and credit bubbles probably raised household debt-to-income ratios to historic highs and decreased the personal savings rate to a historical low, as middle and lower-income households struggled to maintain their standard of living with declining income. High credit usage with low savings rates creates tremendously unstable financial markets, and so could have been the ultimate cause of the Great Recession.

We do have some current research that shows “credit booms gone wrong”, are a major cause of recurrent episodes of financial instability, per a recent NBER Working Paper No. 15512 by Moritz Schularick and Alan Taylor. In “Credit Booms Gone Bust: Monetary Policy, Leverage Cycles and Financial crises, 1870-2008”, Schularick and Taylor maintain that the huge growth in the use of credit and increasingly complex forms of leverage led to an unprecedented level of risk throughout the credit system up to 2008.

The existing evidence seems to imply that the bank panics of 1929-30 and 2007-08 (that burst their respective credit bubbles) were caused by such an unequal distribution of income, as the historical record implies.

Harlan Green © 2010

Posted in Keynesian economics, Macro Economics | Tagged , , , | Leave a comment

Why Financial Reform?

“. . . It is critical to understand that the recent financial crisis was not a natural disaster. It was a man-made economic assault. People did it. Extreme greed was the driving force. It will happen again unless we change the rules,” stated the Chairman of the Senate Permanent Subcommittee on Investigations Carl Levin, Democrat of Michigan.
Congress and the Financial Crisis Inquiry Commission are beginning to understand the dimensions of the financial meltdown of 2008 that almost caused another Great Depression. And crimes have been committed, with only Goldman Sachs being charged with fraud to date for misrepresenting the Collateralized Debt Obligations that it sold to clients.
The just-disclosed SEC fraud case against Goldman is a perfect example of a “man-made economic assault”. On one side, Goldman marketed subprime loan-backed securities to their clients, while on the other side structuring a deal with another client—hedge fund Paulson & Co.—without revealing that Paulson was betting against it and helped to structure the deal, which is omission of at least one “material fact” and so illegal under securities’ laws.
Why the difficulty in pinning down who was responsible, is the question we asked last week. A major source of the problem is the claim the players weren’t responsible for any consequences. Even Alan Greenspan had said the Federal Reserve wasn’t able to detect asset bubbles—the major cause of most financial meltdowns—so how could anyone else detect them? And if not detectable, than how could anyone be held responsible for causing them, and the losses when they burst?
But behavioral economists such as Robert Shiller, et. al., show that the irrational exuberance that creates bubbles is detectable, and preventable with the right regulation. It is true that no one can predict the future, which is why investors have to be able to trust in the institutions that peddle financial investments before investing in them.
And that is the ‘snake oil’ component of financial markets, says 2001 Nobelist George Akerlof in a recent Cambridge University, UK conference. Much of the marketing of investments doesn’t reveal all the facts. The playing field isn’t really level, in other words, and markets are never 100 percent transparent. There are always those—either buyers or sellers—who know more about their products, and may have hidden agendas.
The rating agencies are another example. They caused much of the problem by not downgrading some of the most toxic securities, when they were paid by clients who needed the ratings—a direct conflict of interest.
India’s experience is an example of good regulations. Its Central Reserve Bank did not deregulate derivatives’ trading, and required much higher capital requirements for those who did trade in exotic instruments. Therefore no credit bubble was created, and India was not affected by the worldwide credit bust.
By now, the consequences of the financial meltdown are visible to all—the loss of 8 million plus jobs, $11 trillion in wealth, and a real estate market that will take years to recover in the U.S.. The real estate bubble is just the starkest example. As late as 2007, 2 million new homes per year were being built—much more than were needed even then, driven by easy credit and the irrational exuberance of homebuyers who thought that home prices could only go up. Today the number being constructed is little more than 600,000 units, mostly because the excess supply of the boom years hasn’t yet been sold off.
And the inventory of new homes is still above 9 months supply at current sales’ rates, when the longer term inventory backlog has averaged 6 months.
Whereas, existing home sales are doing better. What Calculated Risk calls the “distressing gap” between new and existing-home sales still exists, because of the tremendous oversupply of homes still on the market—more than 8 months supply at current sales’ rates.
In fact, bubbles can be predicted. No less than Robert Shiller in his 2000 book, “Irrational Exuberance”, predicted the implosion of the dot-com bubble. In the 2005 second edition, he also predicted the bursting of the housing bubble. And it didn’t take sophisticated math.
In the case of stocks, the price-to-earnings ratio had soared to 44 to 1, almost double the 26 to 1 ratio that existed on 1929’s Black Friday. In the case of housing, Shiller saw that housing prices had far outdistanced some fundamental indicators—rising in double digits in mid-2000 when construction costs and population growth rose less than 2 percent per year.
And, in a paper he presented to a Federal Reserve Board economic symposium in August 2007, Shiller warned, “The examples we have of past cycles indicate that major declines in real home prices—even 50 per cent declines in some places—are entirely possible going forward from today or from the not-too-distant future.”
There were numerous others who read the signs, including Bill Gross, Managing Director of PIMCO, the world’s largest bond fund. He criticized the credit ratings of the mortgage-based Collateralized Debt Obligations (one type of insurance derivative) now facing collapse:

“AAA? You were wooed, Mr. Moody’s and Mr.Poor’s,”, he said, “by the makeup, those six-inch hooker heels, and a “tramp stamp (tattoo).  Many of these good-looking girls are not high-class assets worth 100 cents on the dollar… [T]he point is that there are hundreds of billions of dollars of this toxic waste… This problem [ultimately] resides in America’s heartland, with millions and millions of overpriced homes”, said Gross as quoted in Nouriel Rubini’s Global Economics blog.

Many experts predicted both the housing and derivatives collapse, in other words, which was the result of the unregulated derivatives market that operated worldwide. And because unregulated, many of the derivatives had little or no capital backup, which created a domino effect. The collapse of one, caused the collapse of others in a chain reaction.
So the main feature of regulation put forward by both House and Senate bills is greater transparency and more capital to back the transactions. In particular, derivatives, which are bets on the future value of an asset—or even ‘CDO insurance’ (which is really another derivative in this case) that guarantees the derivative, will be reported through a public clearing house just as futures are traded today. And those offering derivatives must have at least 5 percent of their own money in the transaction.
This will not eliminate the greed that is a basic ingredient of human nature, but should discourage excessive greed by making it much more expensive. Taking responsibility means being aware of the consequences to others in the larger economy, not just to oneself.

Harlan Green © 2010

Posted in Keynesian economics, Weekly Financial News | Leave a comment

The Case for Sustainable Economics

Behavioral Economist Robert Shiller said in a recent New York Times Op-ed said, “We need to invent financial institutions that take into account the kinds of communities we want to build. And we need to base this innovation on an approach to economics that captures the richness of human experience—and not efficient-market economics.”
Dr. Shiller is one of many economists decrying the lack of sustainable financial institutions that have led to so many recessions, including the current Great Recession—sustainable institutions that build communities rather than destroy them. Their lack has been mainly because they targeted the wrong economic goals—productivity over sustainability, or efficient markets (i.e. markets with minimal oversight) over markets that attempt to sustain longer-term economic growth.
We seem to have mastered the means of production, as economist John Maynard Keynes predicted in his 1930 treatise, “Economic Possibilities for our Grandchildren”, yet not how to put such growth on a sustainable path that benefits future generations rather than indebting them. As the originator of an economic theory that advocated government support during the Great Depression, Keynes believed that markets did not cure themselves without widespread suffering. The “animal spirits” of a populace that was discouraged by prolonged unemployment had to be boosted by governmental job creation measures in order to boost economic growth, if private sector employers weren’t hiring.
In other words, most modern economic theory has concentrated on producing the maximum amount of goods and services (hence emphasis on efficient markets), but ignoring their social welfare aspects. I.e., how sustainable is such a system that venerates individual effort (i.e., self-interest), but ignores its results? When whole communities are destroyed by a succession of bursting asset bubbles—it was first the dot-com bubble in 2000, then real estate bubble, and now the credit bubble bursting that has almost destroyed our banking system—then it is time to begin looking for a more sustainable economic system that preserves assets for our grandchildren.
Economists, sociologists and psychologists in particular are beginning to look at systems that capture the “richness of human experience” advocated by Dr. Shiller. One pioneer is economist Hazel Henderson, who helped to found the Calvert family of eco-friendly mutual funds. She also created the Calvert-Henderson Quality of Life Indicators (at http://www.calvert-henderson.com) that helps to measure what makes up a better quality of life. Its education component highlights why U.S. elementary education has flagged—the U.S. is ninth in the list of eighth grade math and science scores, for instance—behind nos. 1 and 2 Singapore and Taiwan, and what should be done to remedy it.
The research of behavioral economists such as Dr. Shiller are also debunking the efficient markets’ economists who generally advocate privatization (and deregulation) of financial institutions in the belief that individuals are the best regulators of their own behavior. Behavioral economists find that most people either do not have the time or knowledge to make intelligent financial decisions without some regulation to govern errant behavior. Former Fed Chairman Alan Greenspan once famously said,

“It is not that humans have become any greedier than in generations past. It is that the avenues to express greed had grown so enormously.”

Though private enterprise is the foundation of capitalism, and its source of wealth, we now know it only enriches the few without adequate regulation and governmental oversight.
And so Lord Keynes concludes, “The strenuous purposeful money-makers may carry all of us along with them into the lap of economic abundance. But it will be those peoples, who can keep alive, and cultivate into a fuller perfection, the art of life itself and do not sell themselves for the means of life, who will be able to enjoy the abundance when it comes.”

Harlan Green © 2010

Posted in Uncategorized | Leave a comment

Hello world!

Harlan Green is Editor/publisher of PopularEconomics.com, and contents provider of 3 weekly syndicated columns–Popular Economics Weekly (weekly financial news and analysis), Financial FAQs (readers’ frequently asked financial questions), and The Mortgage Corner (real estate news and issues).  All questions and comments can be directed to:  editor@populareconomics.com.

Posted in Uncategorized | 1 Comment