Third Quarter Growth Will Be Better

Popular Economics Weekly

We now know the reasons for this summer’s growth pause. The Japanese earthquake and Tsunami disrupted a fragile recovery at the same time as Europeans found out they had a fragile banking system. And several stimulus programs had expired—such as the housing tax credits while much of the ARRA $800 billion had been spent. Top that off with congressional gridlock and U.S. credit downgrade, with consumers and businesses still paying down their debt, and we can see why many pundits were calling for a second recession.

clip_image002[6]

But that ain’t happening, folks, as I’ve said. In part, because of all the cash being held by corporations with record profits, and banks in excess reserves. Economic growth for the second quarter ended up stronger than previously estimated but remained anemic, as I’ve said. The Commerce Department’s final estimate for second quarter GDP growth rose 1.3 percent annualized.

But we will see better third quarter economic growth—in the 2 to 3 percent range—as the steady increase in consumer spending (read retail sales) means more businesses will be hiring, while Obama’s new push on allowing more homeowners to refinance—up to 1 million by some estimates—can breathe new life into the housing market.

Expansion of his Home Affordable Refinance Program (HARP) will streamline the refinance process by eliminating appraisals and extensive underwriting requirements for most borrowers, as long as homeowners are current on their mortgage payments, said President Obama at his Las Vegas unveiling. Fannie and Freddie have also agreed to waive some fees that made refinancing less attractive for some.

Pricing details won’t be published until mid-November, and lenders could begin refinancing loans under the retooled program as soon as Dec. 1, according to Calculated Risk. Loans that exceed the current limit of 125 percent of the property’s value won’t be able to participate until early next year. HARP is only open to loans that Fannie and Freddie guaranteed as of June 2009.

It seems that businesses have chosen to get the most out of their current workforce rather than hire new workers. It shows in the flagging productivity numbers and rising unit labor costs (ULC) seen in Econoday’s graph, which means their existing employees cannot produce much more per worker.

clip_image004[7]

This means businesses aren’t hiring more workers because they don’t’ see increasing demand for their products. But the recent pickup in exports, capital goods orders and retail sales are telling us that the Third Quarter will look better.

clip_image006[7]

One reason is industrial production. Manufacturing data point to a stronger third quarter—and no recession. Manufacturing—especially autos—continues to lead industrial production.  In September, industrial production advanced 0.2 percent, following no change the month before and a 1.1 percent jump in July. Manufacturing is outpacing growth for the overall economy over the past year. On a seasonally adjusted year-on-year basis, overall industrial production was up 3.2 percent in September, compared to 3.3 percent in August.  Through the second quarter, real GDP growth was 1.6 percent on a year-ago basis.  Basically, manufacturing is leading the recovery and at the national level is running stronger than implied by manufacturing surveys.

clip_image008

And the excuse given by no-growthers who want to shrink government—that additional stimulus spending will cause inflation—is a canard. We are currently in a deflationary cycle, as Krugman, et. al., have been saying ad nauseum. It is called a liquidity trap when businesses and consumers hold onto their savings rather than spend or invest out of the fear that conditions can worsen again. What will loosen their wallets is some confidence in their future.

Harlan Green © 2011

Posted in Consumers, Economy, Weekly Financial News | Tagged , , , , , , , , | Leave a comment

What will Boost Real Estate?

The Mortgage Corner

Never in my 30 years as a Mortgage Banker did I think I would see interest rates this low—as low as during Harry Truman’s Presidency. Yet very few homeowners are able to take advantage of those rates, which have dropped more than 2 percent since 1997, the beginning of the market crash. And we know why; whether it was the loss of a job, health insurance, or equity in their home with housing values down as much as 50 percent in some states.

This is while the foreclosure backlog is so great it could take more than 60 years in some states to work through, according to New York Times reporter David Streitfeld.

So when two Presidents—President Obama in his new jobs plan, and former President Clinton on the Sunday TV talk shows touting his Clinton Global Initiative—say that real estate has to recover for our economy to recover, it should take precedence in discussions on how to boost economy growth.

And there are concrete steps we can take now to cure much of the housing malaise of vacant homes and deteriorating neighborhoods. Obama’s inclusion of $15 billion in his new jobs plan to rehabilitate depressed neighborhoods is one such. But much more can be done if he can convince Fannie Mae and Freddie Mac to cooperate in loosening some of their almost draconian qualification requirements for both purchase and refinance transactions made more restrictive after the housing crash.

Credit scores, for instance, do not have to be 680 or better, if there are other so-called compensating factors, such as long term employment, or good assets. Or, the almost set-in-stone 45 percent maximum overall debt-to-income ratio could be more flexible with good job security and assets.

And much more can also be done with HARP, the Housing Affordable Refinance Program that was touted to help millions of homeowners, but has helped just 838,000 to date. Hence President Obama’s pronouncement that loan modifications would be allowed for “responsible applicants” can mean that compensating factors should be considered when qualifying borrowers.

But there is another restriction keeping many homeowners from refinancing or buying—the declining equity in their current home. Whereas just 10 years ago average equity was 61 percent, it is now just 38.6 percent, according to the Federal Reserve’s latest Flow of Funds report. If Fannie and Freddie would qualify someone with good credit and assets that is, say, 50 percent underwater, the case in many neighborhoods, then they should be allowed a haircut—meaning a reduction in their principal balance—that would enable them to refinance at today’s record low rates with a new loan that brought it back to 100 percent of current value. The 30-year conforming fixed rate today is hovering at 4 percent.

What is holding Freddie and Fannie back from offering this now, which could in fact refinance an additional 2.9 million homes without significantly increasing tax payers’ liability, according to a recent CBO report? Once again, it seems to be Republicans’ opposition to any more government liabilities, and the fact that an independent agency, the Federal Housing Finance Authority is Fannie and Freddie’s administrator, charged with limiting their losses now that they are government-owned.

But the CBO study showed that it could save homeowners about $7.4 billion in just the first year and help about 111,000 homeowners avoid default with just a net cost of $600 million. What’s not to like about this program?

Harlan Green © 2011

Posted in Economy, housing market, Weekly Financial News | Tagged , , , , , , , , , | Leave a comment

Don’t Accept ‘New Normal’ of Slower Growth

Popular Economics Weekly

There is no reason to accept what pundits and some economists are telling us we have to accept—a ‘new normal’ for economic growth that is some kind of growth recession. Because we have the means to spur sufficient economic growth, if only we will reject an insidious disinformation campaign that discredits all scientific and factual reality, a campaign that can only work if we listen to those who would blame others for the Great Recession—and who would blame immigrants, the budget deficit, too much government, or too high taxes in order to justify further spending cuts.

A growth recession is what the Japanese have experienced ever since their twin real estate and stock bubbles burst circa 2000, because they didn’t cure the ills that caused their bubbles, or spend what it took to revive their economy until it was too late to prevent more than a decade of deflation and poor economic growth.

Japan

Graph: Trading Places

So don’t believe the scapegoaters for a minute. We need more job creation programs, not tax and spending cuts, because corporations are holding onto their record profits generated by laying off domestic workers while sending jobs overseas, so that 50 percent of S&P 500 corporation profits now come from overseas operations. And consumers aren’t spending enough to cause domestic expansion because their incomes aren’t rising, even though they produce more per worker.

The ‘new normal’ of growth we are currently seeing is really a product of the so far successful Republican campaign to oppose any kind of stimulus spending. But they can only do this by dumbing down the electorate or (at least their own constituency) that believes austerity is more important than job creation, that cutting taxes for the richest is more important than repairing our aging infrastructure, or protecting the environment, or even maintaining social security and Medicare.

The Republicans answer to Obama’s $447 billion job formation bill was predictable. House Majority Leader Boehner said long term tax hikes should not pay for short term stimulus, which is not being truthful. The tax hikes are paying for long term jobs—in infrastructure, education and environmental protection. And the tax hikes on itemized deductions for the wealthiest 2 percent would cut some $400 billion from the deficit over the next 10 years, since those tax breaks are being paid for with borrowed money. Another $62 billion of the deficit would be cut by eliminating the various tax breaks on oil and gas, private equity partners, and corporate jets.

Republicans are, in a word, trying to convince us what is in effect a ‘new normal’ of ignorance, a wholesale ignorance of reality based facts—whether economic or scientific. For instance, how can anyone believe Republicans who maintain Obama’s stimulus spending created zero jobs, when the CBO says it created or preserved 1.4 to 4 million “Full Time Equivalent jobs to date? Or Rick Perry’s blatant untruths about social security being a “Ponzi scheme”, global warming not having a scientific consensus when his own Texas is burning because of a record drought, and evolution is just one competing theory?

Their campaign is insidious, as the discounting of facts does appeal to their base of support on the extreme religious right. They have to keep their electorate ignorant, if they want to transfer even more wealth to Wall Street by privatizing social security while advocating deregulation when that is what caused the market crash.

Republican House Whip Eric Cantor tries to justify his opposition to paying for the jobs bill by saying it’s a tax on the “job creators”. But the only job creators will be government tax dollars returning to the private sector to create more private sector jobs, when the private sector isn’t hiring.

And social security and Medicare are really only in danger of running out of funds if Republicans and their conservative backers won’t support the actual reduction of federal debt, rather than keep the tax cuts and loopholes that have transferred so much wealth to the wealthiest, and continue to oppose regulations that would lower health care costs. As a result corporate profits are now highest in history as a percentage of GDP, as we have said.

A growth recession is not what we want. The Japanese are bedeviled by debt that is now 200 percent of GDP, as they have allowed deflation and a cheap currency to facilitate exports, but has suppressed domestic demand—mainly because such a deflationary spiral means their citizens’ wealth continues to decline.

There are other reasons for Japan’s economic decline—reacting too slowly to the bubbles and so choosing austerity instead of pump priming (sound familiar?), static population growth (because of immigration restrictions), and a keiretsu economic system of interlocking ownerships that has banks owning aging corporations they kept afloat too long rather than putting money into new growth opportunities.

But there is no reason we should follow Japan’s example. Instead, we have to turn back 30 years of conservative attempts to shrink government with a vengeance that has not really transferred wealth to the private sector—except to their wealthiest supporters. But it will take the growing anger of the unemployed and under-employed to accomplish it—such as happened with Wisconsin’s public workers—rather than angry Tea Partiers blaming welfare immigrants and the lazy jobless for budget deficits that are only growing because of the disinformation campaign that attempts to dumb down voters.

Harlan Green © 2011

Posted in Economy, Macro Economics, Weekly Financial News | Tagged , , , , , , , , , | Leave a comment

Labor’s Day—Have We Forgotten What It Means?

Popular Economics Weekly

It’s officially the end of summer, start of school, fall colors, and Obama’s upcoming September 8 joint congressional State of the Jobs Market. With the labor market in dire straits, what can we say about this year’s Labor Day Holiday?

Former French Finance Minister and new IMF Managing Director Christine Lagarde gave a highly regarded speech at the Fed’s Jackson Hole conference that said in effect this was the wrong time to implement more austere, budget cutting policies with labor in such trouble. “In the United States, policymakers must strike the right balance between reducing public debt and sustaining the recovery—especially by making a serious dent in long-term unemployment,” she said.

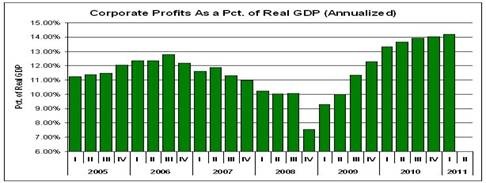
But the latest data on record corporate profits tells us something alarming. Because of the globalization of technology, businesses know how to expand without hiring more employees—at least in this country. About 83 percent of S&P 500 companies have beat second quarter 2011 analyst estimates according to data compiled by Bloomberg News. This is while S&P recently reported that in 2010, 46.3 percent of all S&P 500 company sales originated outside of the US.

“If we look at the last 10 years, the divergence between the corporate profits of S&P 500 companies and domestic GDP growth is astonishing,” said GC Mays, an Independent / boutique research firm analyst in his Seeking Alpha blog. “Between the first Quarter of 2001 and 2006, a simple correlation showed that corporate profits explained 98.4 percent of domestic GDP growth. However, the most recent five years beginning with the first quarter of 2006 the correlation between corporate profits and domestic GDP growth breaks down as corporate profits only explain 10.1 percent of domestic GDP growth.”

clip_image002

Graph:  The Mays Report

Why is it necessary to increase jobs when we now know we can have economic growth without job growth? Well, beside the obvious voter anger if politicos don’t take the lead in creating more jobs, it means taking away the demand that can grow the domestic economy. Corporate profits have risen to the highest level as a percentage of Gross Domestic Product since the Great Depression—14 percent—but much of the profit comes from overseas’ sales of U.S. companies, as we said.

clip_image004

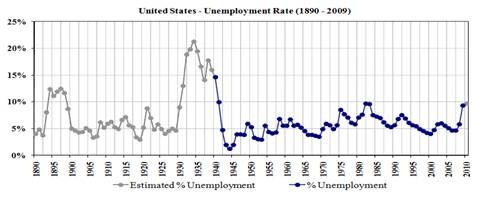
And that doesn’t augur well either for decreasing the record income inequality for most wage earners or growing domestic jobs. Since World War II the unemployment rate has twice reached 10 percent—during the 1981-82 and just ended 2007-09 recession. But because of the housing and financial crashes that accompanied the Great Recession—or Small Depression, as Krugman has christened it—consumers are not spending and employers not hiring domestically as they have in past recoveries.

That means corporate profits are no longer dependent on domestic demand, so are not going to help reduce the various deficits—both household and governmental—without explicit policies to create more domestic jobs. It’s a straightforward equation. Decreasing domestic unemployment means decreasing domestic deficits, and growing household incomes means growing domestic businesses. But since corporations are no longer dependent on growing domestic jobs to sell their products, what policies will? Director Lagarde says it best:

“First—the nexus of fiscal (budget) consolidation and growth. At first blush, these challenges seem contradictory. But they are actually mutually reinforcing. Credible decisions on future consolidation—involving both revenue and expenditure—create space for policies that support growth and jobs today. At the same time, growth is necessary for fiscal credibility—after all, who will believe that commitments to cut spending can survive a lengthy stagnation with prolonged high unemployment and social dissatisfaction?”

We can hope that Labor Day will be a cause for celebration; an international coming together of Big Business and dueling politicians on the need for concrete job creation policies. Make no mistake that as the public becomes better informed on the causes of the current employment malaise, they will seek out leaders who can implement the reforms necessary to correct the imbalance between growing corporate profits and declining payrolls.

“In sum,” concludes Lagarde, “risks to the global economy are rising, but there remains a path to recovery. The policy options are narrower than before but there is a way through. There are lingering uncertainties, but resolute action will help to dispel doubts.”

Harlan Green © 2011

Posted in Economy, Macro Economics, Weekly Financial News | Tagged , , , , , , | Leave a comment

The Fed’s Paralysis—Who Will Do the Right Thing?

Popular Economics Weekly

I actually agreed with Fed Chairman Bernanke in his latest Jackson Hole speech, when he said the Fed can’t grow the economy without some help. The weak growth of late has panicked markets, and Fed policy doesn’t seem to do the trick. Its record low interest rates aren’t helping at the moment, though that is keeping the housing market from dying completely.

So who is setting our monetary and fiscal policy these days? No one, at the moment. The White House is always one step behind events—worrying about deficit reduction when it can’t shrink the deficit without more job growth. And Congress is obsessing about the size of government, when government employment and spending have been shrinking faster than in the private sector.

“The country would be well served by a better process for making fiscal decisions,” was Bernanke’s understatement of the year, signaling it was fiscal policy that should now take the lead in growing the economy. So is Bernanke is throwing up his hands at the moment, in refusing to even hint at what other stimulus policies might come from the Fed until after a special 2-day September convocation of the FOMC? He was putting the policy ball back in the politicians’ court. It’s up to them to settle their differences if they want growth.

It’s of course obvious our ‘lack of a policy’ is now being set by the right wing of the Republican Party, who oppose all forms of stimulus. The downsizing of government has been their agenda since Ronald Reagan, and their only way seems to be by creating recessions. In fact, there have been 5 recessions during the last 3 Republican administrations. Two occurred during Reagan’s presidency (1980, 1981-82), one during Bush I (1991) and two during GW Bush’s presidency (2001, 2007).

Bernanke has been a strong advocate for an active Fed in stimulating economic growth in the past, which is why Nobelist Paul Krugman in effect called him craven for caving in to the Republican extreme right wing. “Now just imagine the reaction if the Fed were to act on the…arguably more important parts of the Bernanke 2000 agenda—more purchases of long term debt (i.e., a QE3), an announcement that short term rates would stay low for an extended period, to further reduce long term rates; and an announcement that the bank was seeking moderate inflation, “setting a target in the 3-4 percent range for inflation, to be maintained for a number of years.”

Bernanke himself actually accused the Bank of Japan at that time of a “self-induced paralysis” in not providing more stimulus to their sputtering economy, according to Krugman. “Well now, the Fed is suffering from externally induced paralysis,” he concludes.

At a time when growth has slowed drastically through the first 2 quarters of 2011 after soaring above 4 percent for several quarters last year, the fears of a double-dip recession is depressing financial markets at the moment. But the outcome is more likely a “growth recession”, defined as slow growth amid rising unemployment that the Japanese have been experiencing for the last 20 years.

clip_image002[6]

Bernanke’s scholarly treatise on the causes of the Great Recession comes at the same time that GDP Q2 growth had just been revised downward to 1 percent from 1.3 percent. “Unfortunately, the recession, besides being extraordinarily severe as well as global in scope, was also unusual in being associated with both a very deep slump in the housing market and a historic financial crisis,” said Bernanke.

Well, duh. How is that new news? He actually pins most of the blame for the current slowdown on the euro debt crisis and S&P downgrade. “It is difficult to judge by how much these developments have affected economic activity thus far, but there seems little doubt that they have hurt household and business confidence and that they pose ongoing risks to growth.” But then he goes on to discuss the need to cure the long term deficit, and only at the end of his speech does he mention the necessity for more job creation to cure the short term deficit due to the Great Recession.

“In the short term, Bernanke said, “putting people back to work reduces the hardships inflicted by difficult economic times and helps ensure that our economy is producing at its full potential rather than leaving productive resources fallow. In the longer term, minimizing the duration of unemployment supports a healthy economy by avoiding some of the erosion of skills and loss of attachment to the labor force that is often associated with long-term unemployment.”

Why so much emphasis on debt, rather than recovery? It is because of timidity on all sides, from the White House and Congress. Even Europe is suffering from the same paralysis in not providing enough aid to Greece, a paralysis that is now spreading through several other countries, says Krugman

“The fiscalization of the crisis story — the insistence, in the teeth of the evidence, that it was about excessive public borrowing — has become an article of faith on both sides of the Atlantic. And that faith has done and will do untold damage.”

So in effect the current slowdown is due to a paralysis of will from our leaders, not lack of monetary and fiscal tools to bring about a sustained recovery.

Harlan Green © 2011

Posted in Economy, Macro Economics, Weekly Financial News | Tagged , , , , , , , | Leave a comment

Our Psychological Depression

Popular Economics Weekly

The plunging financial markets are telling us something depression, but it is more about crowd psychology, than actual events. Americans are very depressed about their financial prospects. Duh, says Paul Krugman, given the congressional deadlock. So why is it causing such market turmoil? I maintain it is because of the unfounded downgrade by Standard & Poors of U.S. Treasury securities to AA+ from AAA. This event has to be almost as shocking as 9/11 to our collective psyches. For just as Bin Laden meant the 9/11 attack to be an attack on our economy, the S&P downgrade means we are no longer the world’s only economic superpower.

So will the downgrade, which hasn’t been matched by either Fitch or Moody’s bond rating services, have an effect on real economic growth is the question. Yale Professor Robert Shiller and other behavioral economists maintain that consumer confidence, or ‘animal spirits’, affects consumers’ behavior. Professor Shiller also says that much of how people judge the economy doesn’t come from facts or economic fundamentals, but the stories they hear, as well as the degree of optimism or pessimism they feel about their own circumstances. For instance, surveys by Professors Shiller and Karl Case in their Macro Markets LLC, show that the housing bubble was fueled in large part by hearsay and media stories that housing values had always risen, and would continue to do so.

clip_image002

So confidence is only one factor that economists look at for their predictions. It’s a good thing, because we are seeing moderate economic growth at the moment and jobs being created. Even retail sales are surging 8 percent annually at the same time that consumer confidence measured by the Conference Board and University of Michigan surveys is at recession-levels.

So it may be that plummeting confidence in financial markets is causing the extreme market volatility of late, rather than economic fundamentals. For instance, the rise in the Consumer Price Index showing some inflation was the reason given for the stock market plunge, along with very negative Empire State and Philadelphia Fed industrial sentiment surveys.

clip_image004

But inflation is also a sign of increasing demand, and prices must rise for businesses to expand. The core CPI index without food and energy fluctuations is up just 1.8 percent annually, while industrial production is still healthy, according to the Federal Reserve. On a year-on-year basis, overall industrial production is rising at 3.7 percent in July. Overall capacity utilization in July also improved to 77.5 percent from 76.9 percent the prior month, signaling that businesses are expanding.

Then why were the Philly and Empire State surveys so pessimistic? It may be that since both surveys are a consensus of managers’ predictions about future prospects, they could also have been affected by the S&P downgrade, which is radiating outward as hedge funds and retirement funds with extensive holdings of Treasury securities also risk being downgraded by S&P, who has decided that it has to make up for allowing AAA ratings on subprime mortgage securities during the housing bubble, thus prolonging it.

clip_image006

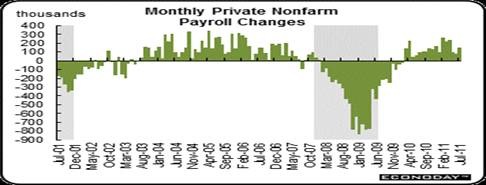
There are also other indicators that show sentiment doesn’t match behavior. Imports are surging, the reason for the larger trade imbalance, which corroborates the higher retail sales’ numbers. And weekly initial unemployment insurance claims continue to fall. Though there was a slight uptick in last week’s claims, the four-week average fell for the seventh straight week, down 3,500 to a 402,500 level that is nearly 20,000 lower than the month ago comparison. In fact, private sector nonfarm payrolls grew 154,000 in July, following an 80,000 rise in June and 99,000 increase in May.

clip_image008

S&P has admitted their downgrade wasn’t really about the numbers, but about their judgement that the political situation could be gridlocked for years to come. This is because the numbers aren’t that bad. Most of the deficit is short term; caused by the Bush tax cuts, ywo unpaid wars and lost revenues from the Great Recession. The wars will end, so defense budgets will shrink, and revenues rise as economic activity continues to pick up. Politicos might also realize that most of those Bush tax breaks should probably be allowed to expire in 2012, rather than be renewed. This in itself would save some $3.8 billion over the next 10 years, according to the Center for Budget and Policy Priorities.

So S&P wasn’t making a judgment about the near term deficit, which they had overestimated by $2 trillion, but about what the federal deficit may look like in 10 years. Yet how can anyone know about events so far into the future? Though given the post-recession frayed nerves of consumers and investors, even the slightest ‘aftershock’ can cause an outsized response.

Harlan Green © 2011

Posted in Economy, Keynesian economics, Macro Economics, Weekly Financial News | Tagged , , , , , , , , | Leave a comment

Don’t Blame Our Democracy…

Popular Economics Weekly

Please don’t blame our Democracy, old as it is—in fact, the oldest in the modern world—for the slowness of this recovery. Winston Churchill on hearing his Labor Party had been defeated in 1947, said in the House of Commons, “Democracy is the worst form of government, except for all those other forms that have been tried from time to time.”

In fact, our Democracy is working, as economic growth is predicted to rise above 3 percent for the rest of the year, and job growth will get better, in spite of the worst downturn since the 1930s. Even real estate is showing signs of life with new housing construction up 14 percent in June.

clip_image002

The Conference Board’s index of leading indicators rose 0.3 percent in June on top of May’s outsized gain of 0.8 percent, which equates to approximately 3 percent growth for the rest of the year. The top factor for June was an increase in money supply with the second factor once again the yield spread between long rates and short rates with the latter being kept near zero by the Federal Reserve. And the larger the spread between short and long term rates—a so-called ‘steep’ yield curve—the more profit for banks and other lenders willing to extend credit.

clip_image004

Housing construction is continuing to move up—but from near rock bottom, says Econoday.  Housing starts jumped 14.6 percent in June, following no change in May.  And this actually helps growth, since it means more jobs. June’s annualized pace of 0.629 million units came in higher than the consensus projection and is up 16.7 percent on a year-ago basis. The boost in June was led by a 30.4 percent surge in the multifamily component.  The single-family component rose 9.4 percent after gaining 0.7 percent the prior month.

Sure, Republicans and Democrats are locked in a struggle that mirrors the eternal struggle between the old and the new. Republicans want every tax break they can get for their wealthiest constituents, while Democrats want every benefits’ break for all the other income classes plus the elderly. And this is preventing both the private and public sectors from stimulating more than tepid growth, in spite of record corporate profits since the end of the Great Recession.

The problem is neither party can agree how to pay for those benefits. Democrats want to close tax loopholes, while Republicans believe putting more money into the pockets of investors and the largest corporations by lowering tax rates further will somehow generate more growth, without spelling out how that might happen. The tax cuts in fact increased the federal deficit in both the Reagan and Bush Administrations

And preserving those Bush tax cuts has increased the deficit some $3 trillion, and will increase it another $7 trillion by 2017, according to the non-partisan Center for Budget Policies and Priorities, if not allowed to lapse.

Even “Read My Lips: No New Taxes” Grover Norquist, leader of those Republicans who have signed his Taxpayer Protection Pledge—which says that he or she will vote against all tax increases—said in a recent New York Times’ Op-ed it doesn’t mean opposing sunset clauses that allow the Bush tax cuts to expire in 2012. “If there were no vote in Congress and taxes rose automatically,” said Norquist, “then no politician would have voted for higher taxes, and no elected official would have broken his or her pledge.”

New York Times Op-ed columnist Charles Blow cited a recent Pew Research poll that said a thin majority of whites are now registered Republicans, while a majority of minorities such as Blacks and Hispanics are registered Democrats. So the line between the past and future is being drawn ever more sharply for the upcoming 2012 presidential election.

As we now know, the debate isn’t really about the deficit, as we said last week, which occurred largely under GW Bush. Else Republicans would be interested in paying down the deficit, which can only be done by closing tax loopholes that have increased the deficit. The federal deficit has been broken down by many, including the non-partisan Center for Budget and Policy Priorities.

clip_image006

New Bush Administration policies accounted for $5.07 trillion of the $14 trillion in Federal debt, while Obama Administration policies such as ARRA accounted for $1.44 trillion. The rest has come from lost revenues of the 2 recessions since 2001. We are now at the lowest level of revenues as a percentage of Gross Domestic Product since WWII.

That is why the debt ceiling agreement has to be ‘balanced’ between cost-cutting and deficit-cutting—i.e., slowing the growth of government programs while closing the tax loopholes that are taking monies away from projects that would stimulate higher growth rates.

Harlan Green © 2011

Posted in Economy, Macro Economics, Weekly Financial News | Tagged , , , , , | Leave a comment

Don’t Blame Fannie and Freddie…

The Mortgage Corner

Please don’t blame Fannie Mae and Freddie Mac, guarantors of most of the housing market’s conventional mortgages and reason the housing market continues to function at all, for the housing bust. The bust was caused by the oversupply of housing built during the bubble, and aggravated by almost all commercial banks and hedge funds cooking up every kind of ‘liar’ loan they could think of to sell to Wall Street securitizers—including to themselves.

Sure, Fannie/Freddie had to be taken over by the federal government and are being subsidized with approximately $167 billion to date, but that is because banks and other commercial lenders then withdrew from financing the housing market, leaving government to clean up the mess. So the government subsidy is a very cheap price to pay to keep housing from collapsing completely.

Credit was too cheap in early 2000, as Fed Chairman Alan Greenspan’s Federal Reserve kept short term interest rates below the inflation rate to pay for the Bush tax cuts and wars. I.e., when short term interest rates were 1-2 percent and inflation in the 3 percent range at the time, it was borrowers who actually profited since inflation deflated the value of the debt. This meant it was interest free money!

Economists have estimated that below inflation interest rates were probably also responsible for the double digit housing price rises during the height of the bubble. Don’t take my word for it. Almost everyone, including the nonpartisan Government Accountability Office, the Harvard Joint Center for Housing Studies, the Financial Crisis Inquiry Commission majority, the Federal Housing Finance Agency, and virtually all academics, have rejected the argument of conservative think tanks such as the American Enterprise Institute that it was federal affordable housing policies designed to make housing available to a broader public, that created so many high risk loans.

Fannie and Freddie created and have always maintained the gold standard of mortgage qualification standards, with the highest income, credit, and ability to pay requirements. As a mortgage banker/broker for 30 years, I have never originated or underwritten a conforming mortgage that didn’t meet those standards.

So why do conservatives hate Fannie and Freddie so much? Because of their ties to the Democratic Party, mainly. As Gretchen Morgenson and Joshua Rosner detail in their book, Reckless Endangerment, Fannie Mae and Freddie Mac grew hugely under Democratic Administrations eager to encourage more affordable housing. And they did buy subprime mortgages from Countrywide Financial that were not underwritten to their conforming underwriting standards, thus fattening their portfolios in a bid to play catchup to the issuers of so-called ‘private label’ mortgages. But the subprime purchases were a drop in the bucket; just $60.8 billion for Freddie Mac, according to David Min of the Center for American Progress, with borrowers who had FICO scores under 620, a common definition of subprime mortgages.

In fact, current delinquency and foreclosure rates of Fannie and Freddie, guarantors of Agency Prime mortgages, are close to the historical norm. Fannie Mae reported that the serious delinquency rate decreased to 4.27 percent in March, close to the long term historical average. This is down from 5.47 percent in March 2010. The Fannie Mae serious delinquency rate peaked in February 2010 at 5.59 percent. Freddie Macclip_image001 reported that the serious delinquency rate decreased to 3.57 percent in April. (Note: Fannie reports a month behind Freddie). This is down from 4.06 percent in March 2010 and Freddie’s serious delinquency rate also peaked in February 2010 at 4.20 percent.

clip_image003

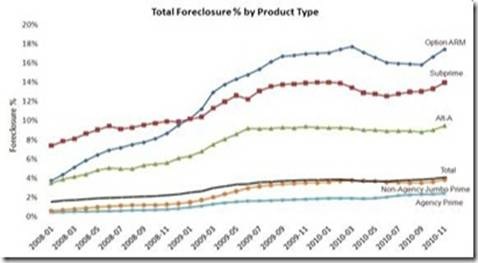
And their foreclosure rates are approaching the 1 percent historical average of all conventional loans. The Calculated Risk graph shows the latest foreclosure rates for all mortgage categories. It may not be surprising that Option ARMs (those with negative amortization that caused the principal loan balance to increased substantially in many cases) have the highest foreclosure rates, even above the Subprimes.

Sadly, Lender Processing Services, Inc. (NYSE: LPS) Mortgage Monitor report shows the number of mortgages 90 or more days delinquent, combined with the foreclosure inventory at the end of June, still totaled 4,073,00 down very slightly from its May 4,084,557 total. It looks like without additional government help, which doesn’t seem likely (see Renae Merle at Washington Post: Obama administration not planning another big housing program), most of those units will be added to the existing home inventory over the next 2 years.

So why doesn’t the Obama Administration spend more of the reportedly $11 billion set aside for the HAMP loan modification program? It may be because Timothy Geithner’s Treasury Department isn’t requiring banks holding the delinquent loans to get them off their books more quickly. And that means not much upside potential for housing prices until when, maybe 2014?

Harlan Green © 2011

Posted in Economy, housing market, Weekly Financial News | Tagged , , , , , , , , , , , , | Leave a comment

It’s Basic Economics, Stupid!

Popular Economics Weekly

What was the reason for Fed Chairman Bernanke’s almost pathetic plea to understand real world economics, in his latest speech at the Atlanta IMF Conference? He said in essence that the Fed is caught between worries about inflation and an economy that is sputtering along. But in fact he was really calling for help!—that he needed help from Obama and Congress to keep economic growth going, because there is still a great danger of deflation than inflation.

If politicians want to obsess over the possibility of future inflation, in other words, then let them tackle the longer term entitlement problems—like Medicare, or foreign wars. But instead they are doing all the wrong things, as are the Europeans. They keep advocating drastic austerity measures while cutting taxes, when that will only depress growth further and expand the deficit (via less tax revenues), not shrink it.

Economic growth has slowed at the moment. But much of this is because of geopolitical uncertainty—the Arab Spring, Mideast oil, the euro bailouts of Greece, Portugal and Ireland, and maybe even our own debt ceiling problem.

But the Federal Reserve’s Beige Book report says most of the U.S. is still growing, retail sales are getting better, consumers and homeowners are paying down debt, and service sector activity in general that provides up to 70 percent of our growth is expanding faster.

Then why the obsession with inflation when it is just gasoline prices that are boosting the CPI index at the moment? Without gas prices the CPI has risen just 1.2 percent in a year. It is the classic battle between creditors and debtors that heats up during recessions. Creditors hate any inflation, since it devalues existing debt. And right now creditors—bankers and other holders of debt on Wall Street—seem to control the agenda. That is why we are hearing cries of austerity and budget cutting–all deflationary measures. Such policies drive down prices, all right, into deflationary spirals such as caused the Great Depression if done at the wrong time—like during this weak recovery.

clip_image002

The best weekly news was the jump in the Institute of Supply Management non-manufacturing (i.e., service-sector) index, which now makes up 70 percent of economic activity. The ISM reported broad month-to-month acceleration in the non-manufacturing economy. The report’s composite headline index rose 1.8 points to 54.6 with strength centered where it should be, that is in new orders which rose more than four points to 56.8.

The ISM employment index also accelerated nicely, up 2.1 points to a 54.0 level that for this report is very strong. In other readings, deliveries lengthened, which is a sign of strength, and backlog orders rose at a healthy pace. Given that this report is based on a broad sampling of the nation’s purchasers, says Econoday, it indicates that economic momentum is headed back up, albeit moderately.

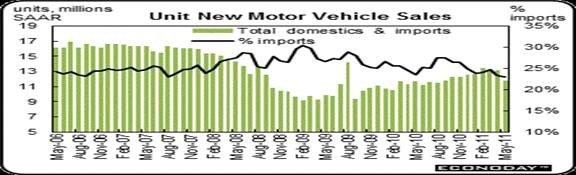
One reason for what looks like a temporary slowdown, is that sales of combined North American-made vehicles and imports dropped to an annualized 11.8 million units from 13.2 million in April.  The North American component declined to 9.1 million from 10.1 million. 

clip_image004

The North American component includes Japanese brands assembled in the U.S. and parts shortages limited supply of many models significantly.  Lack of available Japanese brands pushed up related prices.  This may have convinced many car buyers to wait for the desired model to become available and/or for a lower price, according to analysts.

What is the help that Bernanke’s Fed needs? It can’t do all the heavy lifting, if more fiscal stimulus isn’t forthcoming. A good place to start is forgiving some of the $trillions in delinquent real estate debt incurred during the Great Recession. Real estate is hurting so much because it is estimated 25 percent of home loans are under water—i.e., have more loan than equity in their property. So the quickest way to bring down their debt load—which is holding back consumers spending—is to forgive some amount of the underwater mortgage principal, with some kind of loan modification.

The first quarter 2011 Federal Reserve so-called Flow of Funds report shows just how much is already “forgiven”, in some sense. Much of homeowners’ equity has been lost with so many foreclosures and short sales, of course. But homeowners are also paying down debt in record amounts.

The Fed estimated that the value of household real estateclip_image005 fell $339 billion in Q1 to $16.1 trillion in Q1 2011, from just under $16.5 trillion in Q4 2010. The value of household real estate has fallen $6.6 trillion from the peak – and is still falling in 2011.

In Q1 2011, household percent equity (of household real estate) declined to 38.1 percent as the value of real estate assets fell by $339 billion. A note by Calculated Risk says something less than one-third of households have no mortgage debt. So the approximately 50+ million households with mortgages have far less than 38.1 percent equity – and 10.9 million households have negative equity.

clip_image007

But banks are reluctant to modify loans unless urged by the White House, banking regulators, and/or Congress, even though it is also in their interest to take the delinquent mortgages off their books. And there has been no requirement that mortgage holders/servicers do so, even with the HAMP loan modification program.

Creditors—or rentiers in Europe—were also calling the tune at the beginning the Great Depression in the Hoover Administration. Roosevelt understood this, and instituted inflationary measures by increasing government spending, with regulations that controlled the banking speculation that caused the credit bubble—i.e., highly leveraged bank loans with no regard to risk. It took some inflation to get the economy growing again. In other words, it was the debtors turn to recover, which ultimately brought us out of the Great Depression.

The Roosevelt Administration actually refinanced more than 1 million homes under the Home Owners’ Loan Corporation from 1933-35, with bonds sold to the banks. It also bought many homes lost to foreclosure and rented them back, until they could be sold into the private market. Can we imagine what could be done today with that same political will? One million homeowners then would translate to at least 5 million today, when it is estimated there are no more than 8 million homes in various stages of delinquency. That is, if there is the political will to clean up the real estate mess.

Harlan Green © 2011

Posted in Economy, housing market, Macro Economics, Weekly Financial News | Tagged , , , , , , , | Leave a comment

Where are the Jobs?

Popular Economics Weekly

We know that economic growth has slowed in the first quarter—falling from 3.1 percent growth to 1.8 percent in the second estimate of Q1 GDP growth. But even with slower growth, all sectors are still hiring. And we know there are 3.1 million job openings per the Labor Department’s April JOLT Survey, vs. just 2 million in 2009.

clip_image002

So should we worry about the sharp drop in the Bureau of Labor Statistics’ May unemployment report that said just 54,000 nonfarm payroll jobs were created? Although economists are dismissing seasonal factors such as Tsunamis and tornados; motor vehicles lost 3,400 jobs from the Japanese shutdown of parts factories, 13,000 jobs were lost in ‘nondurable’ goods (retail products, mostly) which could also be attributed to weather factors, and governments shed another 28,000 jobs. State and local governments have now shed 446,000 jobs since September 2008 because of reduced tax revenues.

Calculated Risk gives us the reasons that job creation has slowed but is still growing.

• Initial weekly unemployment claims have averaged 425,500 per week in May, about the same as in December 2010 and January 2011. The BLS reported an average of just over 100 thousand payroll jobs added during those two months (although there were some weather issues in January).
• The ISM manufacturing index slowed sharply in May, however the Institute for Supply Management noted: “Manufacturing employment continues to show good momentum for the year, as the Employment Index registered 58.2 percent, which is 4.5 percentage points lower than the 62.7 percent reported in April.” This suggests manufacturers were still expanding their payrolls in May (the regional manufacturing surveys also showed payroll expansion).

As if to counteract the weak jobs report and ISM manufacturing index, the May ISM service sector index just reported broad month-to-month acceleration in the non-manufacturing economy. The report’s composite headline index rose nearly two points to 54.6 with strength centered where it should be, that is in new orders which rose more than four points to 56.8. Employment, in contrast to this morning’s jobs report, accelerated nicely, up more than two points to a 54.0 level that for this report is very strong. In other readings, deliveries lengthened, which is a sign of strength, and backlog orders rose at a healthy pace.

clip_image004

So the jobs picture is still bad for those still looking for jobs, but wages and hours worked are rising. This means more hiring on the horizon. A few examples of regional reports from Calculated Risk: The Chicago PMI reported: “Breadth of EMPLOYMENT expansion softened but remained strong.” The employment index decreased to a still strong 60.8 from 63.7 (above 50 is expansion). And the Philly Fed reported: “Firms’ responses continue to indicate overall improvement in the labor market despite weaker activity …” and the Empire State survey showed “The index for number of employees inched up to 24.7, indicating that employment levels expanded over the month, and the average workweek index rose thirteen points to 23.7, a multi-year high.” (above 0 is expansion).

WSJ Marketwatch also saw a silver lining in the job numbers. Job demand for different sorts of workers is not the same, so certain jobs and industries are more heavily weighted in some markets than others. Meanwhile, with all of the cuts to state and local governments, public-sector openings are lagging private-sector openings, as we said.

The Monster jobs online jobs index also weakened. But “In San Francisco, we have seen robust private-sector hiring, with IT certainly being huge,” said Monster Worldwide Spokesperson Matthew Henson, according to Marketwatch. “When you look at markets like Pittsburgh and Seattle, there’s a healthy mixture of blue-collar and white-collar jobs. Kansas City is seeing large demand for creative and marketing.”

The 10 ‘hottest’ job markets, according to Monster, are:

1. Washington

2. San Francisco

3. Baltimore

4. Minneapolis

5. Cleveland

6. Boston

7. Seattle

8. Orlando

9. Pittsburgh

10. Kansas City

Harlan Green © 2011

Posted in Economy, Macro Economics, Weekly Financial News | Tagged , , , , | Leave a comment