How Much Has US Economy Slowed?

Financial FAQs

image

Calculated Risk

It’s a difficult question to answer. We know the US economy is slowing, and the manufacturing activity is already contracting—the first of the four indicators that are used to call a recession—per the ISM’s Manufacturing Diffusion Index.

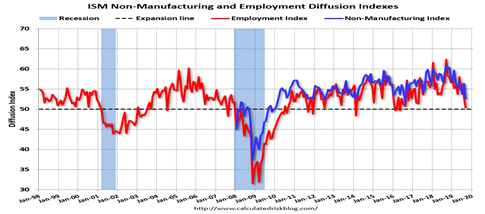
The ISM’s non-manufacturing Indexes still show growth, which is two-thirds of economic activity, but we are close to that edge, as well.

“The NMI® registered 52.6 percent, which is 3.8 percentage points below the August reading of 56.4 percent,” reports Anthony Nieves, Chair of the Institute for Supply Management. “This represents continued growth in the non-manufacturing sector, at a slower rate. The Non-Manufacturing Business Activity Index decreased to 55.2 percent, 6.3 percentage points lower than the August reading of 61.5 percent, reflecting growth for the 122nd consecutive month. The New Orders Index registered 53.7 percent; 6.6 percentage points lower than the reading of 60.3 percent in August. The Employment Index decreased 2.7 percentage points in September to 50.4 percent from the August reading of 53.1 percent. The respondents are mostly concerned about tariffs, labor resources and the direction of the economy,” said Nieves.

image

ADP.com

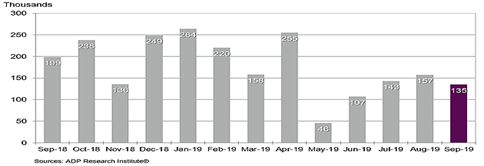
And yesterday’s Associated Data Processing survey came in at 135,000 jobs created, which is a slight downward trend. Just 8,000 jobs were added to the goods-producing sector, whereas 127,000 jobs were added to the service-providing sector, according to ADP.

ADP private payroll survey is usually within 50,000 of the US Bureau of Labor Statistics monthly survey coming out tomorrow, which isn’t much help in predicting the BLS unemployment report.

So there you have it. Employment growth has leveled off. i.e., is no longer increasing. Tomorrow’s report may also show more weakness in job creation.

The 10-year Treasury yield also slipped back into the 1.5 percent range, a sign that there is little demand for credit. Interest rates this low are also a sign of pessimism about future growth, which can be self-fulfilling.

I believe our economy will continue to barely grow, and so avoid an outright recession; at least until next year’s presidential election, when the trade wars might or might not be finally resolved. That seems to be the consensus.

Harlan Green © 2019

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Economy, Macro Economics, Weekly Financial News | Tagged , , , | Leave a comment

Higher Home Sales Mean What?

The Mortgage Corner

image

FRED

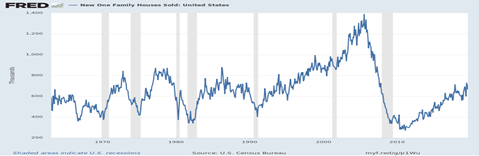
“Sales of new single‐family houses in August 2019 were at a seasonally adjusted annual rate of 713,000, according to estimates released jointly today by the U.S. Census Bureau and the Department of Housing and Urban Development. This is 7.1 percent above the revised July rate of 666,000 and is 18.0 percent above the August 2018 estimate of 604,000. “

A robust housing market could mitigate what is increasingly looking like a looming manufacturing recession due to the ongoing and increasingly contentious trade wars.

Another housing market indicator was also positive, per the National Association of Realtors (NAR). The Pending Home Sales Index, www.nar.realtor/pending-home-sales, a forward-looking indicator based on contract signings, climbed 1.6 percent to 107.3 in August, reversing the prior month’s decrease. Year-over-year contract signings jumped 2.5 percent. An index of 100 is equal to the average level of contract activity.

“It is very encouraging that buyers are responding to exceptionally low interest rates,” said Lawrence Yun, NAR chief economist. “The notable sales slump in the West region over recent years appears to be over. Rising demand will reaccelerate home price appreciation in the absence of more supply.”

This is while the Institute for Supply Management’s manufacturing index fell to 47.8 percent last month from 49.1 percent, marking the lowest level since June 2009, when the Great Recession ended.

“Comments from the panel reflect a continuing decrease in business confidence,” said the report, “…The New Export Orders Index continued to contract strongly, a negative impact on the New Orders Index. Consumption (measured by the Production and Employment indexes) contracted at faster rates, again primarily driven by a lack of demand, contributing negative numbers (a combined 3.3-percentage point decrease) to the PMI® calculation.”

The decline in exports was due to a overall decline in foreign trade. A most recent example of the hurt from that decline was the closing of a Louisiana steel mill because it couldn’t pay for the rising costs of imported scrap steel that it made into finished steel projects, due to the 25 percent tariff (tax) on imported steel.

It remains to be seen whether other business sectors are beginning to contract, as well.

Consumer spending, for example, is on the downward trend, rising just 0.1 percent in August, and 2.3 percent annually, approximately one-half of its 4.8 percent growth rate through the first two quarters, according to the last Q2 GDP estimate. It was the lowest spending in six months, and doesn’t augur well for the rest of the year.

And the latest U-turns in Chinese trade negotiations are coming from Trump’s proposal to limit Chinese company listings on U.S. stock exchanges, which is just one more reason for the increasing uncertainties about future growth.

So I keep wondering how much longer can a healthy housing market and low interest rates keep consumers happily consuming?

Harlan Green © 2019

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Economy, Housing, housing market, Weekly Financial News | Tagged , , , , | Leave a comment

Who’s Willing to predict Q3 GDP?

Financial FAQs

image

FRED.org

We will be lucky to stay at 2 percent growth in this third quarter ending in September. So say a survey of economists, with a PMI Composite FLASH reading of next week’s manufacturing and non-manufacturing surveys flat, consumers spending flat, and consumer sentiment straining to hold onto some semblance of optimism.

Consumer spending is on the downward trend, rising just 0.1 percent in August, and 2.3 percent annually, approximately one-half of its 4.8 percent growth rate through the first two quarters, according to the last Q2 GDP estimate. Its inflation rate remained at 1.8 percent. It was the lowest spending in six months, and doesn’t augur well for the rest of the year.

Why? I mentioned last week that consumers are saving more, spending less out of caution and because a larger percentage live off their savings that yield less with such low interest rates.

But more ominously, the latest U-turns in the Chinese negotiations come from Trump, who is now proposing that at least some of the less transparent Chinese companies be delisted from US stock and bond exchanges. We have no idea at this early stage what that means, since most Chinese companies use the security blanket of being partially owned by the Chinese government to hide their real income and outgo. But it could affect the sales’ volume at least—therefore liquidity?

image

MarketWatch

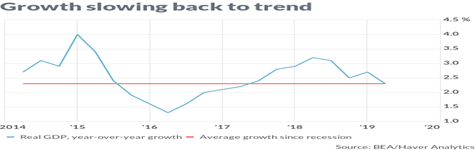
The latest figures show the economy expanded 2.3 percent in the past year, exactly the same pace of the past 10 years since the Great Recession ended, says MarketWatch economist Rex Nutting. With prospects for even slower growth ahead.

“Almost every forecast from professional economists, the Federal Reserve, the Congressional Budget Office, the International Monetary Fund (IMF) and the Organisation for Economic Co-operation and Development (OECD) — but not the White House! — looks for growth of around 2% per year for the foreseeable future,” said Nutting. “ With the growth in the potential labor force slowing from about 1% per year to about 0.2%, it’ll take some very good productivity numbers just to hit 2%.”

A measure of business conditions in the Chicago region, the Chicago PMI index, contracted for the third time in four months, reflecting ongoing struggles by American manufacturers as well as the two-week-old General Motors workers strike. The Chicago PMI business barometer dropped to 47.1 in September from 50.4 in the prior month, MNI Indicators said Monday. Any reading below 50 indicates worsening conditions.

It is a sign that this week’s manufacturing and non-manufacturing (service sector) activity readings will show more weakness ahead.

Let us hope it won’t further dampen consumer confidence for the holidays.

Harlan Green © 2019

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Economy, Weekly Financial News | Leave a comment

Q2 GDP Growth Unchanged

Popular Economics Weekly

image

BEA.gov

In the face of declining consumer confidence, but strong consumer and government spending, the third estimate of second quarter GDP growth was unchanged at 2 percent.

The BEA reported the increase in real GDP in the second quarter reflected positive contributions from personal consumption expenditures (PCE), federal government spending, and state and local government spending that were partly offset by negative contributions from private inventory investment, exports, nonresidential fixed investment and residential fixed investment. Imports, which are a subtraction in the calculation of GDP, increased.

Consumer spending is increasing at 4.6 percent, while government spending that combines federal, state and local outlays is 4.8 percent higher, while inflation is basically flat for a variety of reasons. The PCE price index increased 2.3 percent, compared with an increase of 0.4 percent in the first quarter. Excluding food and energy prices, the PCE price index increased 1.8 percent, compared with an increase of 1.1 percent.

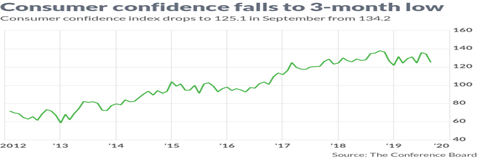
The ‘other’ shoe to drop was the Conference Board’s consumer confidence index that fell to a three-month low of 125.1 this month from 134.2 in August.

image

“Consumer confidence declined in September, following a moderate decrease in August,” said Lynn Franco, Senior Director of Economic Indicators at The Conference Board. “Consumers were less positive in their assessment of current conditions and their expectations regarding the short-term outlook also weakened. The escalation in trade and tariff tensions in late August appears to have rattled consumers. However, this pattern of uncertainty and volatility has persisted for much of the year and it appears confidence is plateauing. While confidence could continue hovering around current levels for months to come, at some point this continued uncertainty will begin to diminish consumers’ confidence in the expansion.” 

That and other indicators show slowing growth—for instance, consumers are saving more of their incomes. This is one factor holding down inflation that was discussed in earlier columns. Seniors are saving more due to extraordinarily low interest rates on which their fixed incomes are dependent, and perhaps more caution about future growth prospects.

Personal saving was $1.32 trillion in the second quarter, compared with $1.37 trillion in the first quarter. The personal saving rate — personal saving as a percentage of disposable personal income — was 8.1 percent in the second quarter, compared with 8.5 percent in the first quarter.

Wholesale inflation has fallen from its high in 2018 as the Trump tax cut stimulus has worn off, though the increase in the core rate of wholesale inflation over the past 12 months rose slightly to 1.9 percent in August from 1.7 percent. Economists prefer core inflation readings because food, gas and trade margins can swing sharply from month to month and mask underlying price trends.

I said last week that six in 10 Americans now say a recession is likely in the next year and as many are concerned about higher prices because of the trade war with China, helping to knock six points off President Donald Trump’s job approval rating in the latest ABC News/Washington Post poll.

This is putting downward pressure on prices, as such fears reduce the demand for goods and services in general. Ratings of the U.S. economy overall, 56 percent positive, are down from 65 percent last fall in this poll, produced for ABC by Langer Research Associates.

Most ominously, 60 percent see a recession as very or somewhat likely in the next year. That’s within sight of the 69 percent who said so in November 2007, one month before the onset of the Great Recession.

Harlan Green © 2019

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Economy, Macro Economics, Weekly Financial News | Tagged , , , | Leave a comment

Strong Home Sales Mean What?

The Mortgage Corner

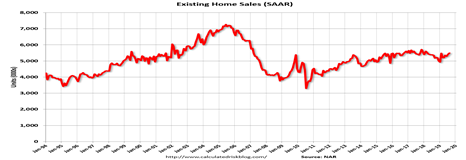
  It looks like home sales are are defying expectations of an economic slowdown, as both existing and pending home sales are rising. Pending sales measure contracts scheduled to close in 30-60 days, which is a sign that home sales should continue to rise for the rest of this year.

image

Calculated Risk

Total existing-home sales, completed transactions that include single-family homes, townhomes, condominiums and co-ops, rose 1.3 percent from July to a seasonally adjusted annual rate of 5.49 million in August. Overall sales are up 2.6 percent from a year ago (5.35 million in August 2018), said the NAR.

It is the second consecutive monthly increase, which is unusual this late in the selling year.  Since housing is usually a leading indicator of economic trends, this could be a good sign for continued economic growth.

Lawrence Yun, NAR’s chief economist, attributed the increase in sales to falling mortgage rates. “As expected, buyers are finding it hard to resist the current rates,” he said. “The desire to take advantage of these promising conditions is leading more buyers to the market.”

The median existing-home price for all housing types in August was $278,200, up 4.7 percent from August 2018 ($265,600). August’s price increase marks the 90th straight month of year-over-year gains.

“Sales are up, but inventory numbers remain low and are thereby pushing up home prices,” said Yun. “Homebuilders need to ramp up new housing, as the failure to increase construction will put home prices in danger of increasing at a faster pace than income.”

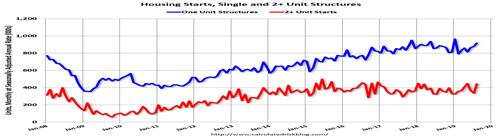
Builders seem to be answering his call, as privately‐owned housing starts in August were at a seasonally adjusted annual rate of 1,364,000. This is 12.3 percent above the revised July estimate of 1,215,000 and is 6.6 percent above the August 2018 rate of 1,279,000 for the strongest residential construction activity in 12 years.

image

Calculated Risk

The report from the Commerce Department on Wednesday also showed permits for future home construction rose to levels last seen in 2007. It added to upbeat data on retail sales that have pointed to an economy that is continuing to grow moderately rather than flirting with a recession as has been flagged by financial markets, said Reuters.

There is still strong demand for new housing, in other words. Builder confidence in the market for newly-built single-family homes rose one point to 68 in September from an upwardly revised August reading of 67, according to the latest National Association of Home Builders/Wells Fargo Housing Market Index (HMI) released on Tuesday. Sentiment levels have held in the mid- to upper 60s since May and September’s reading matches the highest level since last October.

“Solid household formations and attractive mortgage rates are contributing to a positive builder outlook,” said National Association of Home Builders’ (NAHB) Chief Economist Robert Dietz. “However, builders are expressing growing concerns regarding uncertainty stemming from the trade dispute with China. NAHB’s Home Building Geography Index indicates that the slowdown in the manufacturing sector is holding back home construction in some parts of the nation, although there is growth in rural and exurban areas.”

And we mustn’t forget mortgage rates have remained low, with 30-year conforming fixed rates still as low as 3.25 percent, and super-conforming fixed @ 3.375 percent for a one-point origination fee in California. However, there are hints that such rates may begin to rise with the Treasury bond rally slowing. The yield of 10-year benchmark Treasury bonds has increased 30 basis points in just one week.

In fact, the demand for housings still exceeds supply some 10 years after the housing bubble bust, with existing-home inventories back down to a 4-month supply; which is a sign the housing market hasn’t fully recovered from the ensuing Great Recession.

The Fed lowered its Fed Funds rate another 0.25 percent, which dropped the Prime Rate to 4.75 percent. This will encourage consumers to continue spending, in other words, with slightly reduced confidence in future growth and jobs. So it seems smart to buy a home while interest rates remain low and consumer confidence into the holidays.

Harlan Green © 2019

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Economy, Housing, housing market | Tagged , , , , | Leave a comment

Why Make America Small Again?

Popular Economics Weekly

image

ResearchPew

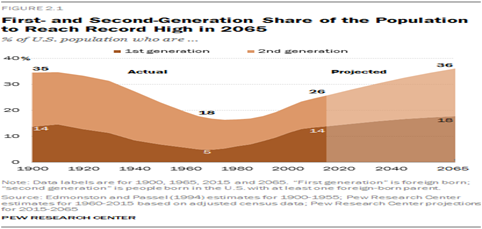
Why make America small again is the question Americans should be asking President Donald Trump whose immigration policies are designed to do just that. He would reduce immigration flows by 50 percent, if he and his conservative supporters have their way.

The result would be stagnating economic growth because of the simple fact that immigrants are the main driver of population growth, due to the low birth rates of native-born Americans.

The U.S. birth rate is 1.8 births per woman, down from 3.65 in 1960, according to the World Bank. Demographers consider 2.1 births per woman as the rate needed to replace the existing population.

image

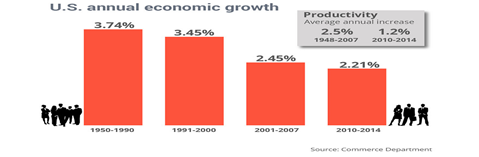
Economic 101 theory states that population growth is one-half of the equation for Gross Domestic Product growth (It’s population growth + productivity = GDP growth). Without adequate population growth, U.S. economic growth would stagnate, as it has in Europe and Japan.

In fact, the Japanese population has been shrinking for decades, which has resulted in a record government debt of some 200 percent of GDP. How else can the Japanese invest in their future but use their government to print money, when its own population contributes a shrinking amount to tax revenues?

And a 2017 report from the National Academies of Sciences, Engineering, and Medicine found immigration “has an overall positive impact on the long-run economic growth in the U.S.”

The best evidence of low native-born birth rates is that over the next five decades, the U.S. immigrant population of 45 million is projected to grow to a record 78 million. The growth rate of 74 percent will be more than double that for the U.S.-born population (30 percent), according to the PEW Study.

Then what does President Trump really believe would make “American Great Again,” if he restricts immigrant inflows, which would reduce U.S. population growth rates by more than half?

He and his supporters labor under a very ancient assumption (not based on fact) that resources are limited in a zero-sum game where one can only gain when others lose a share of income or wealth, or influence, or stature.

That was the mentality of the concentration camp that Nobel Prize-winner Eli Weisal portrayed so graphically in Night, his description of conditions in Nazi death camps as a child.

It is unfortunately a picture that exists today, in which we are imprisoned in a world of declining resources. It also happens to be the mentality of fossil fuel interests that attempt to protect their limited and declining resources—and wealth that are the financial supporters of the Republican Party (such as the Koch Brothers).

They want to protect their very limited resources, whereas renewable energy offers the promise of unlimited energy resources, as does the Information Age and the Internet. This is a world that requires fewer restrictions of people and information across country borders.

American can only be small again in the Trump-Koch Brothers world of the last century, a world that seemed to have limited resources. There’s no part of America that would prosper with 14-foot-high border walls, or trade barriers, or immigration restrictions that are based on win-lose fallacies.

Such walls can only exist for those that still believe they are imprisoned in a past that no longer exists, or has any basis in fact.

Harlan Green © 2019

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Posted in Consumers, Economy, Politics, Uncategorized | Tagged , , , , , | Leave a comment

Retail Sales Rising Again

Popular Economics Weekly

image

Calculated Risk

Retail sales were strong in August from motor vehicle sales, mainly. On a monthly basis, retail sales increased 0.4 percent from July to August (seasonally adjusted), and sales were up 4.1 percent from August 2018, but there was no gain if auto sales are excluded.

We could say the retail boost comes from falling interest rates, as the Fed is scheduled to drop their overnight rate 0.25 percent for a second time this year. It controls the rate on most consumer loans. But should interest rates be pushed down further to keep consumers in the game that are the sole engine of growth these days?

Avi Tiomkin in a very prescient Barron’s article, believes interest rates should be rising and governments spending more, if we want to prevent another Great Recession.

“The primary cause of the deflationary process of the past decade is expansionary monetary policy and ultralow (and negative) interest rates,” he said. “In modern times, monetary policy has been the main instrument used to fight recessions, including the Great Recession that followed the financial crisis of 2008. Central banks lowered rates and infused capital into the markets, but this strategy has exhausted its usefulness and should no longer be applied.”

The result has been near-zero or negative interest rates that exist in many EU countries and Japan, which not only fail to contribute to healthy economic activity but are also causing “omnipresent damages,” said Tiomkin.

The EU and Japan are examples of what happens when interest rates turn negative as their populations age and spend less. This suppresses the overall demand for goods and services. Seniors spend less and save more because of their static savings/pensions when they retire. Lower interest rates lower incomes, in their case, causing them to save more to maintain their income level.

Another way to describe “the deflationary process of the past decade” is the austerity policies initiated after the Great Recession that cut government spending across the board while cutting taxes. It ended up benefitting the one percent, but no one else.

In fact, it led to a second mini-recession in the EU, whereas the U.S. dodged a second recession bullet with the ARRA—The American Reconstruction and Recovery Act of 2010 that momentarily boosted growth with an initial $787 billion put into economic growth that kept many states solvent and boosted infrastructure spending.

But not in the EU, as Germany and the Nordic countries cut back on their spending while penalizing Greece and other heavily-indebted southern EU members for their spending excesses.

So Europe became infected with “austerity mania” rather than formulating a modern Marshall Plan to speed a recovery because of what Nobel economist Paul Krugman described as the “confidence fairy” at the time.

In 2011, the Nobel laureate economist Paul Krugman characterised conservative discourse on budget deficits in terms of “bond vigilantes” and the “confidence fairy.” Unless governments cut their deficits, the bond vigilantes will put the screws to them by forcing up interest rates. But if they do cut, the “confidence fairy” will reward them by stimulating private spending more than the cuts depress it.

However, “Econ 101 said that slashing spending in a depressed economy was a terrible idea,” said Krugman.

Following several years and nearly four trillion euros ($4.4 trillion) of monetary expansion, and negative interest rates, Europe now finds itself on the verge of a recession and a potential political crisis, says Tiomkin. “Persistent deflation, economic weakness, and inequality fomented by a low-rate regime invariably lead to political and social extremism.”

To stem and reverse these trends, governments, led by the U.S., the European Union, and the United Kingdom, must increase spending aggressively in the next few years to spur growth, directing outlays to infrastructure and public services, defense, domestic security, and more.

This prescription for our aging economics has been recommended by other economic giants such as former Harvard President Larry Summers, and Nobelist Joe Stiglitz, who have been lamented the stagnated thinking prevailing among current policymakers.

Old and supposedly sacrosanct budget-deficit ratios—limiting budget deficits to 3% of gross domestic product, for instance—must be ignored, said Tiomkin. They are archaic and detrimental in light of today’s reality.

It took such government programs to recover from the Great Depression and World War II.  How is today any different, after the Greatest Recession since the Great Depression?

Even consumers have limits to what they can spend to keep this recovery alive.

Harlan Green © 2019

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen
Posted in Uncategorized | Leave a comment

Fear of Recession Rises as Wholesale Prices Fall

The Mortgage Corner

image

MarketWatch

The wholesale cost of raw and partly finished goods both fell in August and are negative in the past year, suggesting little inflation in the “pipeline,” according to the Bureau of Labor Statistics.

Wholesale inflation has fallen from its high in 2018 as the Trump tax cut stimulus has worn off, though the increase in the core rate of wholesale inflation over the past 12 months rose slightly to 1.9 percent in August from 1.7 percent. Economists prefer core inflation readings because food, gas and trade margins can swing sharply from month to month and mask underlying price trends.

The reason? President Trump’s trade negotiations have pushed his poll ratings back below 40 percent in the latest ABC News poll. Six in 10 Americans now say a recession is likely in the next year and as many are concerned about higher prices because of the trade war with China, helping to knock 6 points off President Donald Trump’s job approval rating in the latest ABC News/Washington Post poll.

This is actually putting downward pressure on prices, as such fears reduce the demand for goods and services in general. Ratings of the U.S. economy overall, 56 percent positive, are down from 65 percent last fall in this poll, produced for ABC by Langer Research Associates.

Most ominously, 60 percent see a recession as very or somewhat likely in the next year. That’s within sight of the 69 percent who said so in November 2007, one month before the onset of the Great Recession.

In another measure, Trump gets far more criticism than credit for his economic stewardship. Americans by nearly a 3-1 margin, 43-16 percent, say his trade and economic policies have increased rather than decreased the chance of a recession in the next year.

That must be the reason for such low inflation. “Inflation fell earlier in the year and is running short of the Federal Reserve’s 2 percent target,” said MarketWatch, “but the decline in prices may be coming to an end. Some measures of inflation indicate prices could be creeping higher again and economists warn that higher tariffs on Chinese goods could feed into inflation also.”

Is that so? In fact, goods’ wholesale inflation was unchanged, indicating falling demand for manufactured goods that are mainly exported, whereas wholesale service prices overall rose 0.3 percent and were boosted by a 6.4 percent monthly jump in guestroom rental while goods prices fell 0.5 percent overall. Consumers are snapping up domestic purchases, in other words, with soaring retail sales during the approaching holiday season.

The cost of most goods and services are relatively stable, however, and that will give the Fed more room to cut interest rates if the central bank believes the economy needs a boost. The Fed is widely expected to reduce rates next week as an antidote of sorts to the damage caused by the trade war.

Harlan Green © 2019

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen
Posted in Consumers, Economy, Weekly Financial News | Tagged , , , , | Leave a comment

JOLTS Survey Reports Increase in Hiring

Financial FAQs

image

Calculated Risk

This Calculated Risk graph for the Labor Department’s Job Openings and Labor Turnover Survey says (almost) all of it. The yellow line signifying job openings is still soaring far above hires (blue line); so much so that there were still 1.2 million job openings left unfilled in July, the last month surveyed.

Yes, the U.S. economy is so big that there were 5.95 million hires, an increase of 237,000 jobs, and 5.8 million separations that were for a variety of reasons. Many of the separations were voluntary because those employees probably found better jobs.

It’s important to note that the blue columns in the graph show that Quits, or the number of voluntary separations, have been rising since 2010 and are at post-recession highs. Quits are up 3 percent in just the last 12 months.

So we are seeing a very strong job market with that substantial gap between 7.2 million job openings and 5.8 million hires. Hires are still increasing in this 11th year of the recovery from the 2017-19 Great Recession. I.e., there are no signs of weakness in hires that is usually a first sign of contraction.

image

NFIB.com

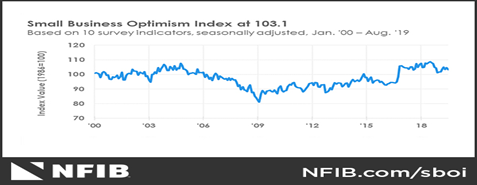
Another jobs indicator, the NFIB Small Business Optimism Index, fell 1.6 points to 103.1, remaining within the top 15 percent of readings, per Calculated Risk, which is important because small businesses create some 80 percent of new jobs.

However, the NFIB reported job creation picked up in August, with an average addition of 0.19 workers per firm compared to 0.12 in July. Finding qualified workers is becoming more and more difficult with a record 27 percent reporting finding qualified workers as their number one problem (up 1 point).

But, “If the widely discussed slowdown occurs, a significant contributor will be the unavailability of labor–hard to call that a “recession” when job openings still exceed job searchers,” said the NFIB.

A further caveat to continued job growth was the Challenger, Gray & Christmas staffing report, which said U.S.-based employers ramped up the pace of downsizing in August, as companies announced plans to cut 53,480 jobs from their payrolls. This is up 37.7 percent from July’s total of 38,845, according to the latest report on job cuts released Thursday.

“Employers are beginning to feel the effects of the trade war and imposed tariffs by the U.S. and China. In fact, trade difficulties were cited as the reason for over 10,000 job cuts in August,” said Andrew Challenger, Vice President of Challenger, Gray & Christmas, Inc.

July was a good month for job formation, in other words, as well as the August unemployment report that showed 130,000 new payroll jobs. However, optimism is slipping among the small business owners that are saying they don’t expect better business conditions and real sales volumes in the coming months.

Harlan Green © 2019

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen
Posted in Consumers, Economy, Weekly Financial News | Tagged , , | Leave a comment

Why Fewer Jobs Created in August?

Popular Economics Weekly

image

MarketWatch

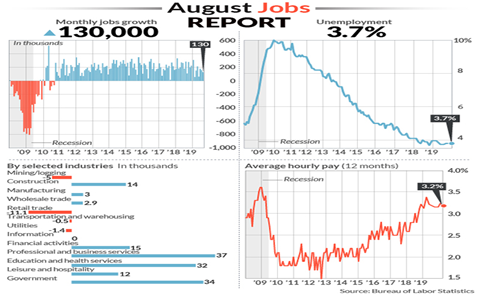
The economy added just 130,000 new jobs in August, marking the smallest increase in three months and offering more evidence that hiring has slowed amid a broadening trade dispute with China that’s disrupted the U.S. and global economies, is the ‘lede’ story this Friday.

There were also downward revisions to the last 2 months, the BLS said. The change in total nonfarm payroll employment for June was revised down by 15,000 from +193,000 to +178,000, and the change for July was revised down by 5,000 from +164,000 to +159,000.

The soft employment figures should keep the Federal Reserve on track to cut interest rates later this month, even after another sharp increase in wages.

Longer term interest rates are already plunging and there is speculation that rates might even trend lower, particularly if the Fed continues to lower short term rates. It could boost home sales and prices, as well, if no recession looms due to the other factors (trade war?).

Harvard economics Professor Kenneth Rogoff said recently that it isn’t out of realm of possibility that more Central Banks might introduce negative interest rate yields to prevent another recession as is already the case in the EU and Japan, as I’ve been saying.

Average hourly earnings for all employees on private nonfarm payrolls rose by 11 cents to $28.11, following 9-cent gains in both June and July. Over the past 12 months, average hourly earnings have increased by 3.2 percent, said the Bureau of Labor Statistics (BLS), also.

Federal Reserve Chairman Jerome Powell said Friday afternoon that the most recent monthly gauge of the U.S. labor market fit into an overall picture of a healthy jobs market and economy.

In a question-and-answer session in Zurich, Powell said the outlook for the economy remains favorable, describing the future as one likely to reflect continued moderate economic expansion.

Then why the downward trend in hiring? Nobel economist Paul Krugman says that Trump’s trade policies are bad for productive business, in particular, which are businesses that must plan for the longer term. That excludes extractive businesses, like oil and coal mining that only think short term; which means until the oil and coal reserves run out.

“Trump’s trade war isn’t just that tariffs raise costs and prices,” said Krugman, “while foreign retaliation is cutting off access to important markets. It is that businesses can’t make plans when policy zigzags in response to the president’s whims.”

The gain in new jobs was even weaker if hiring tied to the upcoming U.S. Census is stripped out. In August, employment in federal government rose, largely reflecting the hiring of temporary workers for the 2020 Census. Private-sector employment was up by 96,000, with notable job gains in health care and financial activities and a job loss in mining.

There are other factors slowing job growth to consider, also. No national infrastructure bill has been passed, when that would be the surest way to jump-start employment in productive businesses. But it means spending government money, and the Trump administration only wants to spend taxpayers’ money on border walls; even attempting to take away some $3.4 billion from the defense budget to do so.

So this could just be the beginning of slower job growth, if the trade wars aren’t resolved soon, as I and many others have been saying. But who will resolve them in time to prevent that R word from surfacing, once again?

Harlan Green © 2019

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen
Posted in Consumers, Economy, Weekly Financial News | Tagged , , | Leave a comment